
Updated October 2026
Many small businesses that fail are profitable on paper. They run out of cash because a big customer paid late, a tax bill arrived that nobody saved for, or growth tied up money in stock and wages before the sales came in. Good financial planning isn’t about complicated spreadsheets. It’s about knowing where your money is, where it’s going, and what’s coming next, early enough to act.
This guide gives you an eight-step plan, with worked examples you can copy, and a simple monthly routine that keeps you in control.
The 8-step plan at a glance
Table of Contents
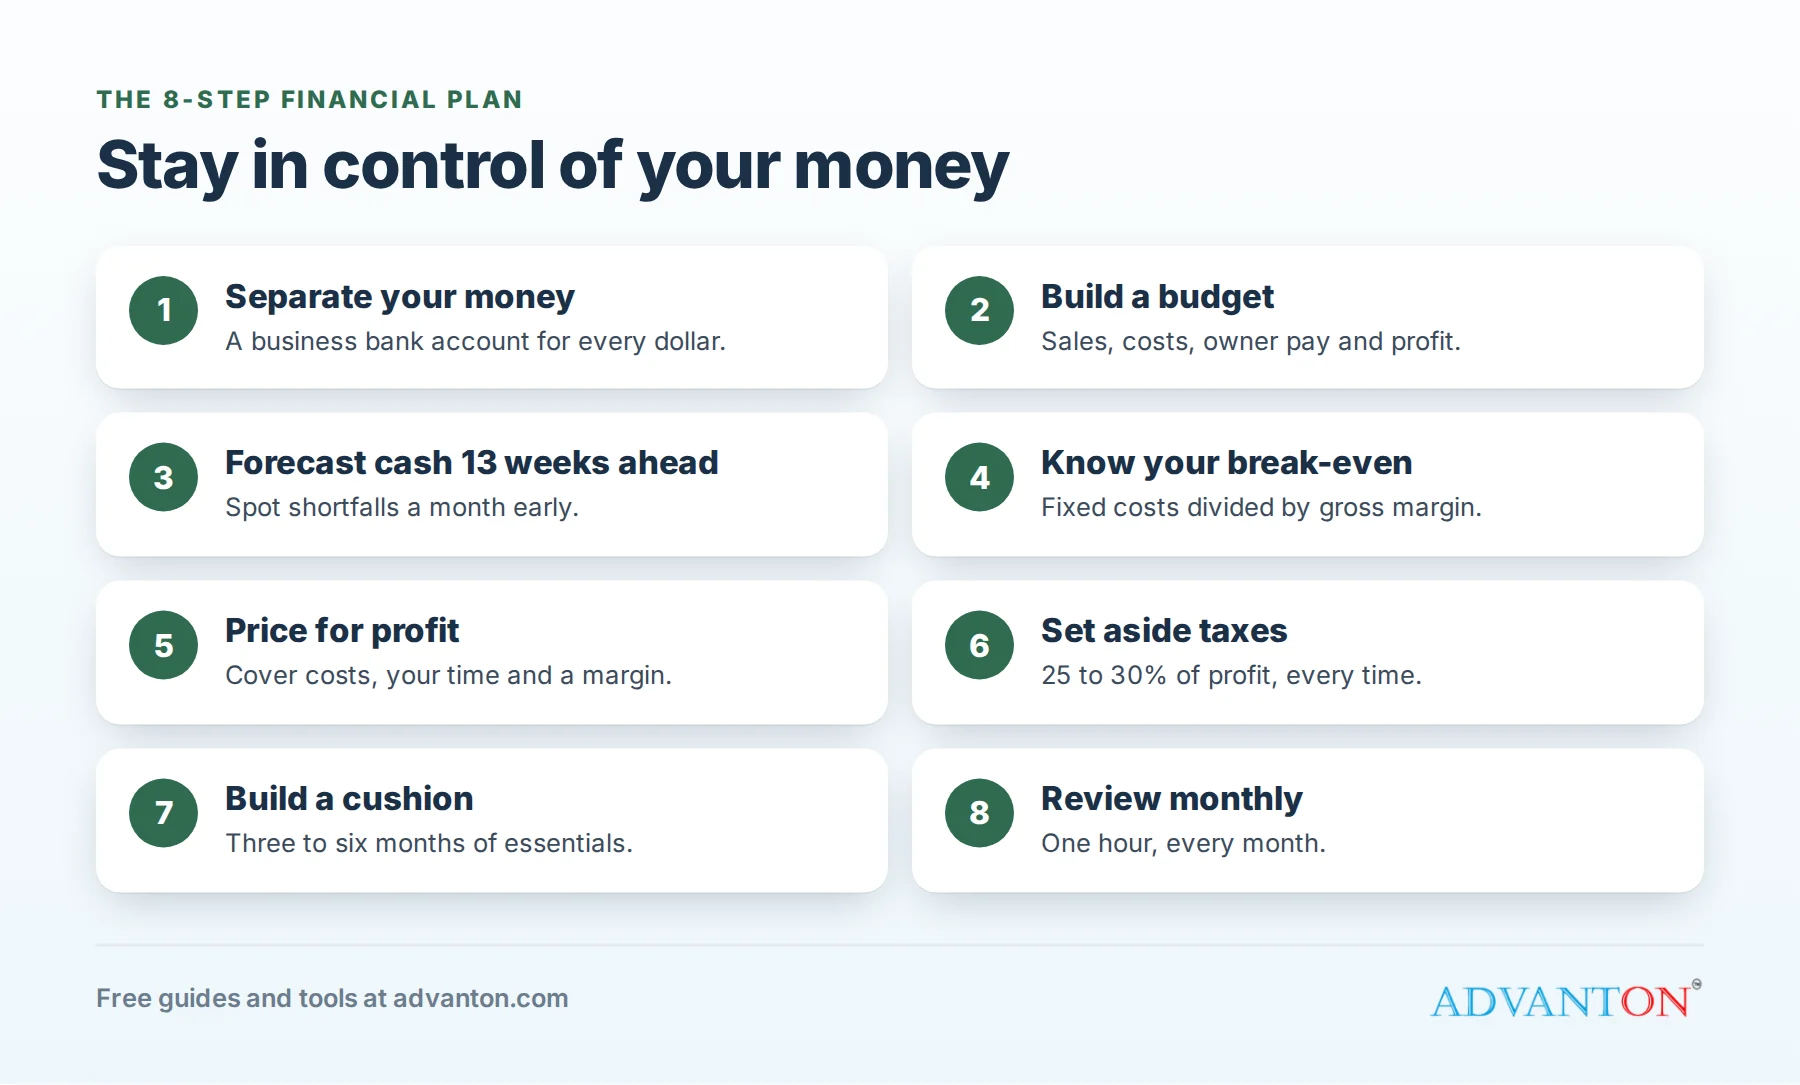
- Separate business and personal money.
- Build a simple budget.
- Forecast cash flow 13 weeks ahead.
- Know your break-even point.
- Price for profit.
- Set money aside for taxes.
- Build an emergency cushion.
- Review your numbers every month.
Step 1: Separate business and personal money
Open a business bank account and run every business dollar through it. It makes bookkeeping and taxes far easier, gives you a true picture of how the business is doing, and, for an LLC or corporation, helps protect your personal assets. Pay yourself by transfer, never by paying personal bills from the business account. See how to open a business bank account.
Step 2: Build a simple budget
A budget is your plan for the year: expected sales, and what you’ll spend to get them. Keep it to one page:
| Line | What to include |
|---|---|
| Sales | Monthly sales by product or service, based on last year or realistic estimates |
| Cost of sales | Materials, stock and subcontractors that rise with sales |
| Gross profit | Sales minus cost of sales |
| Fixed costs | Rent, insurance, software, phone, loan payments, salaries |
| Owner pay | What you’ll pay yourself |
| Profit | What’s left, before taxes |
Compare actual results with the budget every month. The differences tell you where to act.
Step 3: Forecast cash flow 13 weeks ahead
Profit and cash aren’t the same. A 13-week cash flow forecast shows money in and out week by week, so you can see a shortfall coming while there’s still time to fix it.
A worked example (illustrative numbers):
| Week | Cash at start | Money in | Money out | Cash at end |
|---|---|---|---|---|
| 1 | $12,000 | $6,000 | $7,500 | $10,500 |
| 2 | $10,500 | $4,000 | $9,000 (payroll and rent) | $5,500 |
| 3 | $5,500 | $3,000 | $4,500 | $4,000 |
| 4 | $4,000 | $2,500 | $9,500 (payroll, quarterly tax) | -$3,000 |
The forecast spots week 4’s shortfall a month early. The owner can chase overdue invoices, ask a customer for a deposit, delay a purchase, or arrange a line of credit before it’s needed. Update the forecast every week by rolling it forward.
Step 4: Know your break-even point
Your break-even point is the sales you need just to cover your costs. The formula:
Break-even sales = Fixed costs ÷ Gross margin percentage
Example: a business with $8,000 in monthly fixed costs and a 40% gross margin needs $20,000 in monthly sales to break even. Every dollar of sales above that adds 40 cents of profit. Our free break-even calculator does the math for you.
Step 5: Price for profit
Many small businesses underprice, especially services. Build prices from your real costs, including your own time, overhead and a profit margin, rather than copying competitors. Review prices at least once a year, and when your costs rise. Our pricing calculator and guide to product line pricing can help.
Step 6: Set money aside for taxes
Taxes are the most common surprise for new owners. If you’re self-employed, you’ll usually pay self-employment tax (12.4% Social Security tax on net earnings up to $184,500 in 2026, plus 2.9% Medicare), plus federal and often state income tax. Most owners who expect to owe at least $1,000 must pay estimated taxes quarterly, usually due April 15, June 15, September 15 and January 15.
A simple habit: move 25% to 30% of profit into a separate tax savings account every time you’re paid, then pay estimated taxes from it. Ask your accountant for the right percentage for you, and adjust it once you’ve filed your first year’s return and know your real tax rate.
Step 7: Build an emergency cushion
Aim for three to six months of essential expenses in a separate savings account. Start small: even one month’s rent and payroll set aside gives you breathing room for a slow season, a late-paying customer or an equipment failure.
Step 8: Review your numbers every month
Set a recurring one-hour "money meeting" with yourself (and your bookkeeper or partner). Review:
- Profit and loss: sales, gross margin and profit versus budget.
- Cash: current balance and the 13-week forecast.
- Money owed to you: invoices more than 30 days overdue.
- Money you owe: bills, loans and upcoming taxes.
- Three key numbers for your business, such as average sale, customers per week or jobs per crew.
Five numbers to watch
| Number | How to calculate it | What it tells you |
|---|---|---|
| Gross margin | (Sales − cost of sales) ÷ sales | How much of each sale is left to cover overhead and profit |
| Net profit margin | Net profit ÷ sales | How profitable the business really is after all costs |
| Current ratio | Current assets ÷ current liabilities | Whether you can pay bills due in the next year; above 1.5 is usually comfortable |
| Days sales outstanding | (Money owed to you ÷ sales) × days in the period | How long customers take to pay; rising numbers mean cash is tied up |
| Months of cash runway | Cash ÷ average monthly spending | How long you could keep going if sales slowed |
You don’t need all of them on day one. Start with gross margin and cash runway, and add others as you grow.
When cash runs short: your options
Plan these before you need them, because lenders are far more willing to help a business that isn’t yet in trouble:
- Speed up money coming in: invoice immediately, take deposits on large jobs, offer online payment, and follow up on overdue invoices every week.
- A business line of credit: flexible borrowing for short gaps, arranged while your finances look healthy.
- SBA microloans and other SBA-backed loans: for working capital and equipment, through SBA-approved lenders.
- Invoice financing or factoring: an advance against unpaid invoices, useful for businesses with slow-paying commercial customers, but expensive, so compare costs carefully.
- Business credit cards: convenient for short-term purchases, but costly if you carry a balance.
- Negotiate: suppliers and landlords will often agree to short delays if you ask early and honestly.
Avoid funding ongoing losses with debt. If the business consistently loses money, fix pricing or costs first.
Your monthly money routine
| When | What to do |
|---|---|
| Weekly | Categorize transactions, send invoices, chase overdue ones, update the cash forecast |
| Monthly | Reconcile accounts, review profit and loss against budget, move tax and emergency savings |
| Quarterly | Pay estimated taxes, review prices and costs, check the budget for the rest of the year |
| Yearly | Set next year’s budget, review insurance and banking, meet your accountant before year-end |
Common financial planning mistakes
- Treating cash in the bank as profit, then spending money set aside for taxes or bills.
- Growing too fast without the cash to fund stock, staff and slow-paying customers.
- Not charging enough, so even busy months barely break even.
- Ignoring late payers. Clear payment terms and polite reminders protect your cash; see best invoicing software.
- Borrowing for losses instead of fixing pricing or costs.
When to get help
A good accountant or bookkeeper pays for themselves when you’re setting up your books, choosing a business structure, planning for taxes, borrowing money or growing quickly. The SBA’s local partners, including SCORE mentors and Small Business Development Centers, offer free or low-cost advice on financial planning.
Frequently asked questions
How much cash should a small business keep?
Enough to cover at least one to three months of essential expenses in your operating account, with a further emergency fund of three to six months over time, plus your tax savings.
What’s the difference between a budget and a cash flow forecast?
A budget plans income and expenses for the year; a cash flow forecast tracks when money actually arrives and leaves, week by week, so you can see shortfalls before they happen.
What software do I need?
Accounting software for your books and a simple spreadsheet for your budget and cash flow forecast are enough for most small businesses. See best free accounting software.
How do I pay myself?
Sole proprietors and single-member LLC owners usually take owner’s draws by transfer; S corporation owners pay themselves a reasonable salary through payroll. Pay yourself regularly, from profit, after setting aside taxes.
How often should I update my budget?
Review it monthly against actual results, and update the forecast for the rest of the year each quarter or whenever something big changes, such as a new major customer, a price change or a new hire.
Should I use my personal savings to fund the business?
Many owners do at the start. Record it properly as an owner’s contribution or a loan to the business, keep personal emergency savings separate, and decide in advance how much you’re willing to put in.
Keep learning
Related guides
Sources
- US Small Business Administration, Manage your finances
- IRS, Estimated taxes
- Journal of Accountancy, Social Security wage base for 2026
Last reviewed October 28, 2026. Startup costs are estimates; check local prices, licensing and tax rules before you commit money.


Leave a Reply