
An independent insurance agency sells insurance from multiple insurance companies (carriers), helping clients compare options for auto, home, renters, life, business and other coverage. Unlike captive agents who represent one company, independent agents can shop the market for each client.
Agencies earn commissions on new policies and, importantly, on renewals, so a well-run agency builds a valuable recurring book of business over time. The hard parts are licensing, gaining access to carriers as a new agency and growing the first book. The Bureau of Labor Statistics reports a median pay of $60,370 for insurance sales agents (May 2024). Agency owners earn commissions on the policies their agency places, so income depends on the size of the book of business and retention. This guide covers licensing, carrier access, insurance and compliance, economics, technology, marketing, a worked example and a 90-day plan.
An independent insurance agency at a glance
Table of Contents
| Topic | What to expect |
|---|---|
| Startup cost | Moderate: licensing, agency license, E&O insurance, agency management system, network fees, marketing and working capital |
| Licensing | State producer licenses for each line, an agency entity license and nonresident licenses for other states |
| Carrier access | Direct carrier appointments, or an agency network or aggregator that provides access to multiple carriers |
| How you earn | Commissions on new and renewal policies, sometimes bonuses based on growth and profitability |
| Best for | Licensed, sales-minded people who enjoy advising clients and building long-term relationships |
Who an independent agency suits
It suits people who enjoy sales and service, explain complex topics simply and build long relationships. Many owners start as captive or employed agents, learning the business before going independent.
Independent vs captive
Captive agents represent one insurance company, which often provides leads, training and branding. Independent agents contract with multiple carriers and own their book of business, so clients and renewals belong to the agency, subject to its carrier contracts. Ownership of the book is what makes independent agencies valuable over time.
Licensing
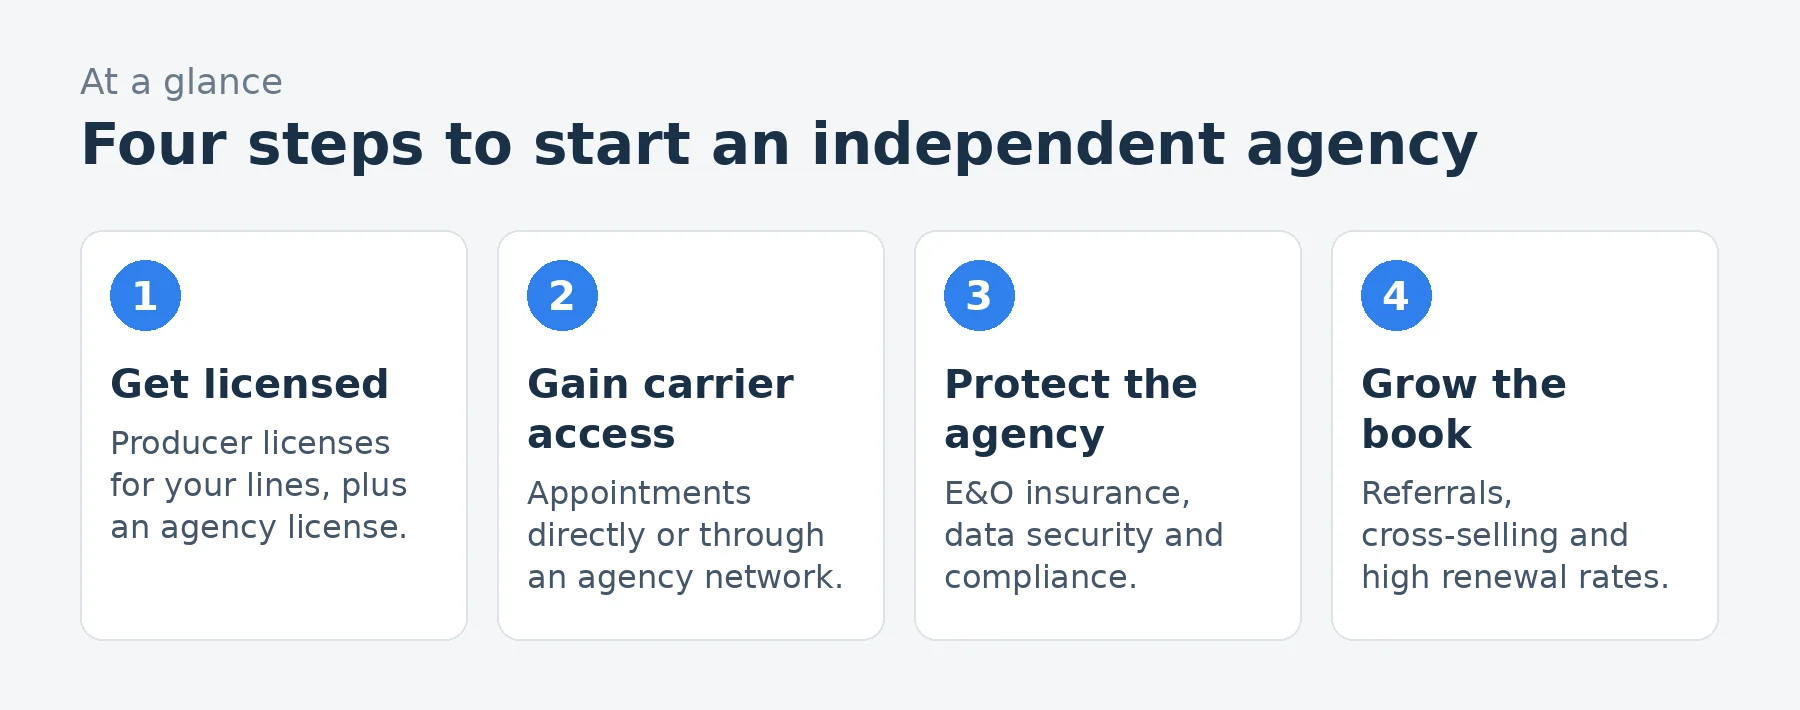
Insurance agents (producers) must be licensed by their state for each line they sell, such as property and casualty or life and health. Licensing usually involves pre-licensing education in many states, a state exam, a background check and fingerprints, then continuing education to renew. Agencies typically need a business entity license and a designated responsible licensed producer. Selling to clients in other states requires nonresident licenses, which many agents manage through NIPR. Agents also need appointments with insurance companies to sell their products.
Getting carrier access
Many carriers require new agencies to show premium volume or experience before appointing them directly. New agencies often join an agency network, cluster or aggregator, which provides access to multiple carriers in exchange for a share of commissions or fees, along with training and support. Compare networks on carrier lineup, commission split, fees, ownership of your book and exit terms.
E&O insurance and data security
Carry errors and omissions (E&O) insurance, which many carriers require before appointing an agency, because mistakes in coverage advice or paperwork can leave clients uninsured. Protect clients’ personal information: insurance agencies are covered by privacy and data security rules, including state insurance data security laws modeled on NAIC standards in many states, and the FTC Safeguards Rule applies to some financial businesses.
Choosing your lines
- Personal lines: auto, home, renters, umbrella and recreational vehicles.
- Commercial lines: business owners policies, general liability, workers’ compensation, commercial auto and professional liability.
- Life and health: life insurance, disability and health coverage.
- Specialty niches: restaurants, contractors, trucking, nonprofits or high-value homes.
Many agencies start with personal lines and add commercial lines, which pay larger commissions per client and renew reliably.
Startup costs to plan for
| Item | What to budget for |
|---|---|
| Licensing | Pre-licensing courses, exams, fingerprints, agency license |
| E&O insurance | Required by most carriers and networks |
| Network fees | Joining fees or commission splits |
| Technology | Agency management system, comparative raters, CRM |
| Office | Office or virtual setup, phones |
| Working capital | Months of expenses while commissions build |
Use our startup cost calculator for your total.
How agency revenue works
Carriers pay commissions as a percentage of premium, often higher on new business than renewals for some lines, and some pay contingent or profit-sharing bonuses. Because revenue accumulates as policies renew, agencies typically take several years to reach strong profitability. Track retention, policies per client and premium growth.
A worked example: a three-year-old agency
These are illustrative assumptions for an agency about three years in, not predictions; commission rates vary by carrier and line.
| Assumption | Monthly | |
|---|---|---|
| Commissions on new business | About $30,000 in new monthly premium at an average 12% commission | $3,600 |
| Renewal commissions | About $140,000 in renewing monthly premium at an average 11% | $15,400 |
| Revenue | $19,000 | |
| Network or aggregator share | Share of commissions paid for carrier access | $(1,900) |
| Customer service representative | Licensed, with payroll costs | $(4,200) |
| Agency management system and raters | $(600) | |
| E&O insurance | $(300) | |
| Office, phone and software | $(1,100) | |
| Marketing and lead costs | $(1,500) | |
| Profit before owner pay and taxes | $9,400 |
That leaves about $9,400 a month before the owner’s pay and taxes, on about $19,000 of commission revenue. Renewals are the engine: keeping clients year after year matters more than any single sale.
Loading the calculator…
Technology
An agency management system tracks clients, policies, renewals and commissions, while comparative raters let you quote several carriers at once. Add e-signature, client portals and a CRM for follow-ups. Good systems let a small team serve many clients.
Marketing and lead generation
- Referrals from clients, real estate agents, mortgage lenders and auto dealers.
- Local presence: Google Business Profile, reviews and community involvement.
- Niches where you become the known specialist.
- Cross-selling home and auto, umbrella and business coverage.
- Purchased leads, used carefully, following telemarketing rules for calls and texts.
Retention
Annual reviews, quick claims help, proactive remarketing when rates rise and responsive service keep clients. Clients with several policies at your agency are far more likely to stay.
Buying a book of business
Instead of starting from zero, some agents buy a book of business from a retiring agent. Review the book’s retention, carrier mix, premium, commission history and client demographics, confirm carrier approvals for the transfer and plan a careful client introduction. Financing options exist for agency acquisitions.
A service model that scales
As the agency grows, separate sales from service: producers find new clients, while licensed account managers handle renewals, changes and certificates. Documented workflows, an agency management system and response time standards keep service consistent.
What an agency is worth
Agencies are often valued based on recurring commission revenue, retention, growth and profitability. Building strong retention and clean records increases what your agency could be worth if you ever sell.
Hiring licensed staff
Anyone who discusses coverage, quotes or binds policies generally needs a license, so plan to hire licensed customer service representatives or support new hires through licensing. Clear roles for licensed and unlicensed staff keep the agency compliant.
Common mistakes to avoid
- Selling without the right license for each line and state.
- Joining a network without reading book ownership and exit terms.
- Skipping E&O insurance.
- Weak data security for client information.
- Underestimating how long it takes to build a renewal book.
Your first 90 days
- Days 1-30: complete pre-licensing and exams, and form your agency and apply for its license.
- Days 31-60: compare networks and carriers, buy E&O insurance and set up an agency management system.
- Days 61-90: launch locally, build referral partnerships and write your first policies.
Frequently asked questions
How do I get licensed to sell insurance?
Complete any required pre-licensing education, pass your state’s exam for each line, pass a background check and apply for the license, then keep up with continuing education.
How do new agencies get access to insurance companies?
Through direct appointments where carriers allow, or by joining an agency network or aggregator that provides access to multiple carriers.
Do independent agents own their book of business?
Usually yes, subject to carrier and network contracts; read ownership and exit terms carefully.
How do insurance agencies make money?
Through commissions on new and renewal policies, sometimes plus bonuses for growth and profitability.
Do I need E&O insurance?
Yes. Most carriers require errors and omissions coverage, and it protects you from claims of coverage mistakes.
How long does it take to build an agency?
Several years, typically, since renewal commissions accumulate as the book grows.
Can I buy an existing insurance book of business?
Yes. Many agents buy books from retiring agents, with carrier approval and careful review of retention and commissions.
Can I start an insurance agency from home?
Yes, many independent agents work from home or virtual offices, subject to state agency licensing and carrier requirements.
What lines should a new agency start with?
Many start with personal auto and home, then add commercial lines and life insurance as they gain experience and carrier access.
Do I need my own carrier contracts?
Not at first. Many new agencies use networks or aggregators for carrier access, then seek direct appointments as volume grows.
Keep learning
- Insurance agencies industry data
- How to start a commercial insurance agency
- How to start a health insurance brokerage business
- Startup cost calculator
Sources
- NAIC, Producer licensing
- NIPR (National Insurance Producer Registry), Licensing and appointments
- US Bureau of Labor Statistics, Insurance sales agents
- Big "I" (Independent Insurance Agents and Brokers of America)
- FTC, FTC Safeguards Rule: what your business needs to know
Last reviewed November 3, 2026. Startup costs are estimates; check local prices, licensing and tax rules before you commit money.

