
A commercial insurance agency helps businesses protect themselves: general liability, property, workers’ compensation, commercial auto, professional liability, cyber, umbrella and specialty coverage for their industries. Business clients need expert advice, pay larger premiums than most individuals and renew year after year, which makes commercial lines a strong foundation for an agency.
Commercial insurance rewards expertise: understanding a client’s operations, contracts and risks, and placing coverage with the right carriers, including the surplus lines market for hard-to-place risks, which requires an additional license. The Bureau of Labor Statistics reports a median pay of $60,370 for insurance sales agents (May 2024). Agency owners earn commissions on the policies their agency places, so income depends on the size of the book of business and retention. This guide covers licensing, markets, niches, coverage, service, economics, a worked example and a 90-day plan.
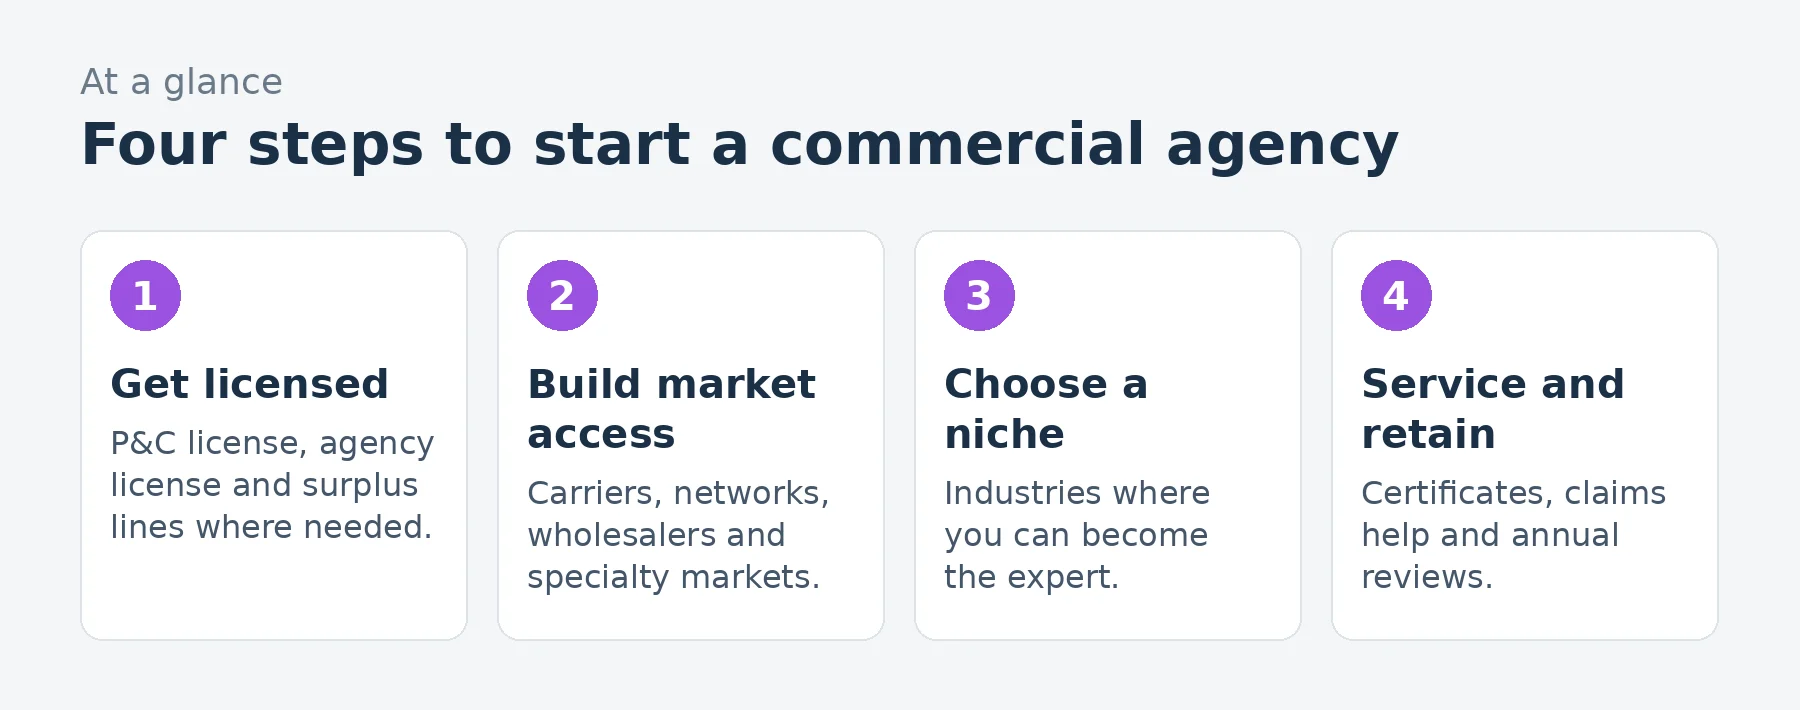
A commercial insurance agency at a glance
Table of Contents
| Topic | What to expect |
|---|---|
| Startup cost | Moderate: licensing, agency license, E&O insurance, network or market access, technology and working capital |
| Licensing | Property and casualty producer license, agency license and a surplus lines license to place non-admitted coverage |
| Market access | Direct carrier appointments, agency networks, wholesale brokers and managing general agents |
| How you earn | Commissions on new and renewal premium, sometimes fees where permitted and contingent bonuses |
| Best for | Business-minded advisors who enjoy learning industries and solving risk problems |
Who commercial insurance suits
It suits people who enjoy business conversations, learning how different industries operate and solving complex problems. Many commercial producers come from underwriting, claims or personal lines agencies.
Licensing
Insurance agents (producers) must be licensed by their state for each line they sell, and commercial insurance requires a property and casualty license. Licensing usually involves pre-licensing education in many states, a state exam, a background check and fingerprints, then continuing education to renew. Agencies typically need a business entity license and a designated responsible licensed producer. Selling to clients in other states requires nonresident licenses, which many agents manage through NIPR. Agents also need appointments with insurance companies to sell their products.
To place coverage with non-admitted (surplus lines) carriers, for risks the standard market will not cover, you need a surplus lines broker license in most states, and you must follow rules on diligent search, disclosures, filings and surplus lines taxes. Many agents place these risks through licensed wholesale brokers.
Admitted, non-admitted and specialty markets
- Admitted carriers are licensed in the state, with rates and forms regulated and state guaranty fund protection.
- Non-admitted (surplus lines) carriers cover unusual or high-risk exposures with more flexibility, accessed with the right license or through wholesalers.
- Wholesale brokers and managing general agents (MGAs) provide access to specialty and surplus markets for retail agents.
- Agency networks help new agencies access multiple carriers in exchange for commission shares or fees.
Coverage types to know
- Business owners policy (BOP): property and liability for small businesses.
- General liability and umbrella or excess liability.
- Workers’ compensation, required for employers in most states.
- Commercial auto for business vehicles and fleets.
- Professional liability (errors and omissions) for service businesses.
- Cyber liability, increasingly required by clients and contracts.
- Inland marine, builders risk, liquor liability and industry-specific coverage.
Choosing a niche
Specializing in industries such as contractors, restaurants, trucking, real estate, healthcare practices or technology firms lets you learn their risks, contracts and carriers deeply. Niche expertise wins clients, improves placements and supports referrals within the industry.
E&O insurance and data security
Carry errors and omissions (E&O) insurance, which many carriers require before appointing an agency, because mistakes in coverage advice or paperwork can leave clients uninsured. Protect clients’ personal information: insurance agencies are covered by privacy and data security rules, including state insurance data security laws modeled on NAIC standards in many states, and the FTC Safeguards Rule applies to some financial businesses.
Startup costs to plan for
| Item | What to budget for |
|---|---|
| Licensing | P&C and surplus lines licenses, agency license |
| E&O insurance | Required by carriers and networks |
| Market access | Network fees or commission shares |
| Technology | Agency management system, certificate tools, raters |
| Designations | Coursework such as CIC or CPCU |
| Working capital | Expenses while the book grows |
Use our startup cost calculator for your total.
The commercial sales process
- Learn the business: operations, revenue, employees, vehicles, contracts and claims history.
- Review current policies and gaps.
- Complete applications and market the account to suitable carriers.
- Present options with clear explanations of coverage differences.
- Bind coverage, issue certificates and set up service.
Start marketing renewals early, often 60 to 90 days before expiration, especially for larger accounts.
A worked example: a three-year-old agency
These are illustrative assumptions for an agency about three years in, not predictions; commission rates vary by carrier, line and market.
| Assumption | Monthly | |
|---|---|---|
| New business commissions | About $25,000 in new monthly premium at an average 13% | $3,250 |
| Renewal commissions | About $160,000 in renewing monthly premium at an average 12% | $19,200 |
| Revenue | $22,450 | |
| Network, wholesaler and market costs | Commission shares and fees | $(2,400) |
| Account manager | Licensed, with payroll costs | $(5,000) |
| Agency management system and tools | $(700) | |
| E&O insurance | $(400) | |
| Office, phone and software | $(1,200) | |
| Marketing and association memberships | $(1,300) | |
| Profit before owner pay and taxes | $11,450 |
That leaves about $11,450 a month before the owner’s pay and taxes, on about $22,450 of commission revenue. Commercial accounts are larger and stickier than personal lines, so each retained account adds lasting value.
Loading the calculator…
Certificates of insurance and contracts
Business clients constantly need certificates of insurance for customers, landlords and general contractors, often with additional insured requirements. Fast, accurate certificates and help reviewing insurance requirements in contracts are among the most valued services, and errors here are a common source of E&O claims.
Claims and risk management
Help clients report claims promptly, follow up with adjusters and learn from losses. Simple risk management (safety programs, contract review and driver policies) can reduce claims and premiums and strengthens loyalty.
Professional designations
Designations such as the CIC (Certified Insurance Counselor) and CPCU (Chartered Property Casualty Underwriter) deepen technical knowledge and add credibility with business clients and carriers.
Finding clients
- Industry associations in your niche.
- Referral partners: accountants, attorneys, bankers and commercial real estate brokers.
- Existing personal lines clients who own businesses.
- Contract-driven needs: businesses that must meet insurance requirements to win work.
- Local business groups and chambers of commerce.
Workers’ compensation audits
Workers’ compensation premiums are based on estimated payroll and job classifications, then audited after the policy year. Help clients classify employees correctly and estimate payroll accurately, so they avoid surprise audit bills that damage trust.
Cyber coverage conversations
Many small businesses underestimate cyber risk. Explaining ransomware, funds transfer fraud and data breach costs, and the security controls insurers now require, opens conversations about cyber coverage and adds value beyond traditional lines.
Annual stewardship reviews
Meet business clients before each renewal to review changes in operations, revenue, employees, vehicles, locations and contracts. These reviews prevent coverage gaps, find new coverage needs and show clients the value of an expert agent.
Common mistakes to avoid
- Placing surplus lines coverage without the right license or filings.
- Weak review of contract insurance requirements.
- Certificate errors.
- Marketing renewals too late.
- Trying to serve every industry without expertise.
Your first 90 days
- Days 1-30: obtain your P&C license and agency license, and study your target niche.
- Days 31-60: secure market access through carriers, a network and a wholesaler, and buy E&O insurance.
- Days 61-90: meet referral partners in your niche and quote your first business accounts.
Frequently asked questions
What license do I need to sell commercial insurance?
A property and casualty producer license, an agency license and usually a surplus lines license to place non-admitted coverage.
What is surplus lines insurance?
Coverage from non-admitted carriers for risks the standard market will not cover, requiring a surplus lines license and specific filings.
How do commercial agents get access to carriers?
Through direct appointments, agency networks, wholesale brokers and managing general agents.
What coverage do most small businesses need?
Often a business owners policy, general liability, workers’ compensation if they have employees, commercial auto and professional or cyber coverage depending on the business.
What is a certificate of insurance?
A document showing a business’s coverage, often requested by customers, landlords and contractors.
Should I specialize?
Yes. Niche expertise in industries such as contractors or restaurants helps win and keep commercial clients.
How long does it take to build a commercial book?
Usually several years, though larger commercial accounts can grow revenue faster than personal lines.
Do commercial agents need E&O insurance?
Yes. Commercial coverage advice is complex, and E&O insurance is required by most carriers and networks.
What is a business owners policy?
A package policy combining property and general liability coverage for eligible small businesses, often at a lower cost than separate policies.
What designations help commercial agents?
The CIC and CPCU are widely respected and deepen technical knowledge of commercial coverage.
Keep learning
- Insurance agencies industry data
- How to start an independent insurance agency
- How to start a business consulting firm
- Startup cost calculator
Sources
- NAIC, Producer licensing
- NAIC, Surplus lines
- NIPR (National Insurance Producer Registry), Licensing and appointments
- The Institutes, CPCU designation
- US Bureau of Labor Statistics, Insurance sales agents
- FTC, FTC Safeguards Rule: what your business needs to know
Last reviewed November 3, 2026. Startup costs are estimates; check local prices, licensing and tax rules before you commit money.

