
Every homeowner, driver and business needs insurance, and contractors need several types: general liability, workers’ compensation, commercial auto and more. Insurance agencies earn commissions on new policies and renewals, building recurring revenue over time. The Bureau of Labor Statistics reported a median wage of $60,370 for insurance sales agents in May 2024.
Agencies range from solo agents to independent agencies representing many carriers, and specialists in commercial lines. Licensing, carrier appointments and a steady flow of referrals are the foundations.
The workforce
| Occupation | Jobs (2024) | Median pay (May 2024) | Projected growth, 2024 to 2034 |
|---|---|---|---|
| Insurance sales agents | n/a | $60,370 | n/a |
Source: U.S. Bureau of Labor Statistics, Occupational Outlook Handbook.
Business models compared
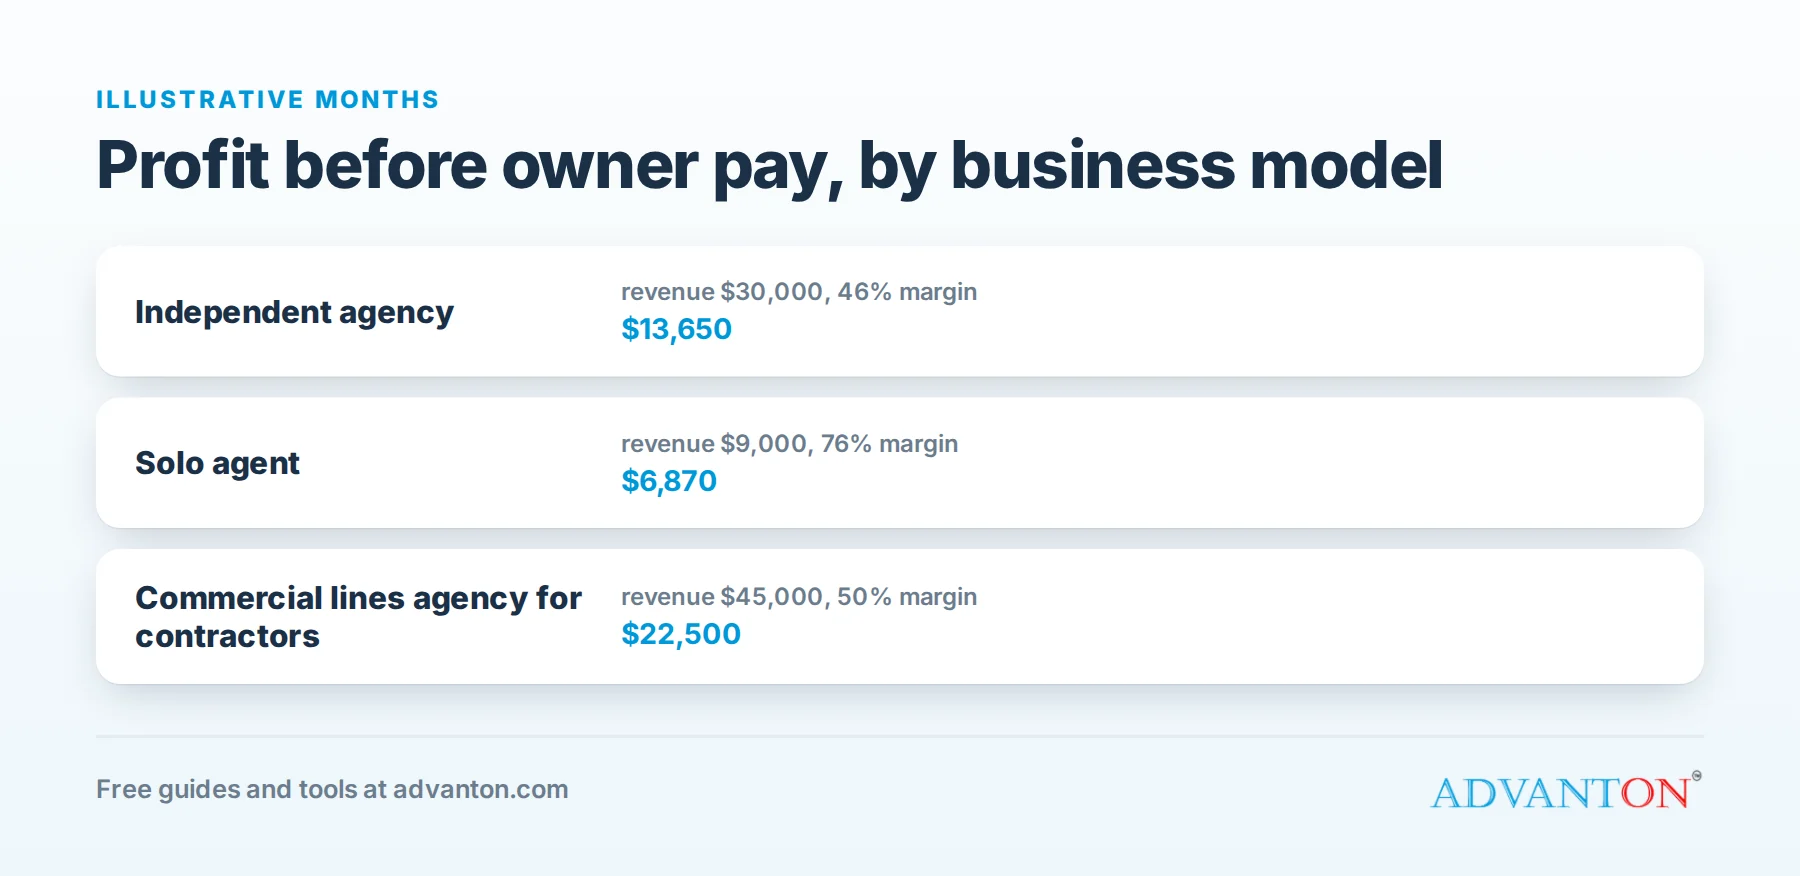
The figures below are illustrative months from our step-by-step guides, not industry averages. They show how revenue and costs typically fit together; your market, prices and costs will differ.
| Business model | Startup costs | Example monthly revenue | Costs | Profit before owner pay | Margin |
|---|---|---|---|---|---|
| Independent agency (owner plus 2 staff) | Low to moderate: licenses, carrier appointments, agency software, E&O insurance | $30,000 | $16,350 | $13,650 | 46% |
| Solo agent (captive or independent) | Low: license, appointments, software | $9,000 | $2,130 | $6,870 | 76% |
| Commercial lines agency for contractors | Moderate: commercial expertise, carrier access, licensed staff | $45,000 | $22,500 | $22,500 | 50% |
Fixed and variable costs
For projections, the most useful split is between variable costs, which rise and fall with sales (materials, parts, hourly labor), and fixed costs, which you pay every month regardless (rent, salaried staff, insurance, loan payments).
| Business model | Variable costs (% of revenue) | Fixed costs per month | What it means |
|---|---|---|---|
| Independent agency (owner plus 2 staff) | 0.0% | $16,350 | Mostly fixed: slow start-up months are expensive |
| Solo agent (captive or independent) | 0.0% | $2,130 | Low costs overall: time is the main constraint |
| Commercial lines agency for contractors | 0.0% | $22,500 | Mostly fixed: slow start-up months are expensive |
What the numbers say
Renewals build the business. Commissions on renewals mean each retained client keeps paying year after year.
Staff and marketing come first. Agencies pay for staff, software and lead generation before their book of business matures.
Commercial lines carry larger policies. Contractors and businesses need multiple coverages and annual reviews.
The three models in brief
Independent agency. Personal and commercial lines from several carriers.
Solo agent. Low overhead, often focused on personal lines.
Commercial lines for contractors. Liability, workers’ comp, auto and bonds for trades. See insurance leads.
Cost structure: independent agency (owner plus 2 staff)
Each cost as a share of the example month’s revenue ($30,000):
| Cost | Monthly amount | Share of revenue | Type |
|---|---|---|---|
| Staff | $9,000 | 30.0% | Fixed |
| Marketing and leads | $2,500 | 8.3% | Fixed |
| Payroll taxes and benefits | $1,800 | 6.0% | Fixed |
| Office | $1,800 | 6.0% | Fixed |
| Agency management software | $700 | 2.3% | Fixed |
| E&O insurance | $400 | 1.3% | Fixed |
| Licensing and education | $150 | 0.5% | Fixed |
| Profit before owner pay | $13,650 | 46% |
A first-year projection: independent agency (owner plus 2 staff)
New businesses rarely start at full speed. This projection assumes revenue ramps from 35% of the example month in month 1 to 100% by month 12, variable costs move with revenue, and fixed costs stay the same every month. It’s a planning illustration, not a forecast.
| Month | Revenue | Variable costs | Fixed costs | Profit | Cumulative |
|---|---|---|---|---|---|
| 1 | $10,500 | $0 | $16,350 | -$5,850 | -$5,850 |
| 2 | $13,500 | $0 | $16,350 | -$2,850 | -$8,700 |
| 3 | $16,500 | $0 | $16,350 | $150 | -$8,550 |
| 4 | $18,600 | $0 | $16,350 | $2,250 | -$6,300 |
| 5 | $21,000 | $0 | $16,350 | $4,650 | -$1,650 |
| 6 | $22,800 | $0 | $16,350 | $6,450 | $4,800 |
| 7 | $24,600 | $0 | $16,350 | $8,250 | $13,050 |
| 8 | $26,100 | $0 | $16,350 | $9,750 | $22,800 |
| 9 | $27,300 | $0 | $16,350 | $10,950 | $33,750 |
| 10 | $28,500 | $0 | $16,350 | $12,150 | $45,900 |
| 11 | $29,400 | $0 | $16,350 | $13,050 | $58,950 |
| 12 | $30,000 | $0 | $16,350 | $13,650 | $72,600 |
Year one: revenue $268,800, profit before owner pay $72,600. The first profitable month is month 3. Cumulative results bottom out at -$8,700, which is the minimum cash cushion this plan would need, before any startup costs.
This independent agency illustration turns profitable in month 3, with a cumulative low of about $8,700. Real agencies usually take longer, because revenue grows as the book of policies and renewals builds; plan conservatively.
How agencies earn
- New business commissions on policies sold.
- Renewal commissions each year a client stays.
- Contingent or bonus commissions from some carriers.
- Fees where state law allows.
A startup checklist
- Get licensed for each line of authority you’ll sell.
- Obtain carrier appointments or join a network that provides access.
- Choose agency management and quoting software.
- Buy errors and omissions insurance.
- Build referral partnerships with real estate agents, lenders, dealers and contractors.
Where the opportunities are
- Contractor insurance packages and certificates.
- Small business insurance for local firms.
- Bundled home and auto reviews.
- Life and benefits for existing clients.
Key terms
| Term | Meaning |
|---|---|
| Carrier appointment | Authorization to sell a company’s policies |
| Book of business | The policies an agency manages |
| Retention | The share of clients who renew |
| Certificate of insurance | Proof of coverage contractors give clients |
Service keeps clients
Fast certificates, clear explanations and help at claim time keep clients renewing for years.
Marketing an agency
Referrals, partnerships and local search bring steady clients. See insurance leads.
Annual reviews grow accounts
Reviewing coverage each year finds gaps and opportunities, and keeps clients from shopping elsewhere.
How to use these numbers for your own plan
- Start with the closest model above and its cost structure.
- Replace every price and cost with local quotes: insurance, wages, vehicles, materials and your expected prices.
- Estimate your ramp: how many jobs you can realistically win each month in year one.
- Separate fixed and variable costs, then calculate your break-even point with our free break-even calculator.
- Map cash month by month with our cash flow forecast, including equipment and loan payments.
- Build the plan in our free Business Planner.
These figures will also feed a planned Advanton projection tool, so you’ll be able to start from an industry template and adjust it to your situation.
About this data
Workforce figures come from the U.S. Bureau of Labor Statistics (Occupational Outlook Handbook and Occupational Employment and Wage Statistics, May 2024 and the 2024 to 2034 projections). Market figures cite their sources in the list above. Business model figures are illustrative months built from typical prices and costs to show how revenue, fixed costs and variable costs fit together; they are not industry averages or guarantees. We review these profiles when new government data is released, at least once a year. The same figures are available in a structured format for Advanton’s upcoming business projection tool.
Licensing and rules
State insurance producer licenses for each line of authority; carrier appointments; continuing education; errors and omissions insurance; state rules on referral fees and rebating. Requirements change; confirm with your state and local agencies before you start.
Frequently asked questions
What do insurance agents earn?
BLS reported a median of $60,370 in May 2024.
Do insurance agents need a license?
Yes, a state producer license for each line of authority.
How do agencies make recurring revenue?
Renewal commissions on policies clients keep.
How can I use these numbers?
Start with the closest insurance agency model, then replace every figure with your local prices, commissions, wages and expected volume.
Keep learning
- Independent agency
- Local SEO for contractors
- How to get more contractor leads
- Specialty trades industry data
Sources
Last reviewed October 30, 2026. Startup costs are estimates; check local prices, licensing and tax rules before you commit money.

