
Ask a group of small business owners how they cut their tax bill and someone will mention the S corporation. Used well, it can save a profitable owner thousands of dollars a year in self-employment tax. Used too early, or set up badly, it adds costs and paperwork that wipe out the savings, and it can draw IRS attention if your salary is unrealistically low.
This guide explains exactly how the S corporation election works in 2026, who qualifies, the deadline, the "reasonable salary" rule, the real costs, and worked examples showing when it pays off.
This is general information, not tax advice. Talk to a CPA, who can run the numbers for your situation and state, before you elect.
What an S corporation is
Table of Contents
"S corporation" isn’t a type of business you form with your state. It’s a federal tax status, named after Subchapter S of the tax code, that an eligible corporation or LLC chooses by filing Form 2553 with the IRS. Once elected, the business:
- Pays no federal income tax itself (with rare exceptions). Profit and losses pass through to the owners’ personal returns, as with an LLC.
- Pays owners who work in the business a salary through payroll, with Social Security and Medicare taxes withheld and matched.
- Can distribute remaining profit to owners as distributions, which are not subject to self-employment or payroll taxes.
That last point is the whole reason most small businesses elect.
How it saves money
Without the election, the owner of a sole proprietorship or LLC pays self-employment tax on all business profit. In 2026 that means 12.4% Social Security tax on net earnings up to $184,500, plus 2.9% Medicare tax on all net earnings, calculated on 92.35% of profit, with half of the tax deductible.
With the election, only the salary you pay yourself is subject to those payroll taxes (6.2% plus 1.45%, paid by both the business and you, for the same 15.3% combined). Profit above your salary, taken as distributions, avoids them. The more your profit exceeds a reasonable salary, the bigger the saving.
Who can elect S corporation status
Generally, the business must:
- Be a domestic corporation, or an LLC that elects to be taxed as a corporation (the Form 2553 filing covers this).
- Have no more than 100 shareholders.
- Have only allowable shareholders: individuals who are US citizens or residents, certain trusts and estates, and certain tax-exempt organizations, but not partnerships, corporations or nonresident aliens.
- Have only one class of stock: every share has the same rights to distributions and liquidation proceeds.
Certain businesses, such as some banks and insurance companies, are ineligible.
The deadline
File Form 2553 no more than 2 months and 15 days after the beginning of the tax year you want the election to start, or at any time during the year before. For a calendar-year business, that usually means by March 15. A new business counts from the day it began (for example, its formation date). All shareholders must sign.
Missed it? The IRS offers relief for late elections in many cases if you have reasonable cause, and the Form 2553 instructions explain how to request it. Otherwise, the election takes effect the following year.
The reasonable salary rule
The IRS requires S corporation owners who work in the business to pay themselves reasonable compensation for the services they provide, before taking distributions. There’s no set formula, but factors include your duties, time spent, experience, what similar businesses pay for similar work and what you’d have to pay someone else to do your job.
Paying yourself a token salary (or none) while taking large distributions is a well-known IRS audit target, and the IRS can recharacterize distributions as wages, with back taxes and penalties. Document how you set your salary, for example with salary surveys or job postings for similar roles in your area.
The real costs of an S corporation
| Cost | What it involves |
|---|---|
| Payroll | Running payroll for yourself: withholding, payroll tax deposits, quarterly Form 941 filings, W-2s, and state unemployment insurance in most states. A payroll service usually handles this; see best payroll software |
| Business tax return | Form 1120-S each year (due March 15 for calendar-year businesses), plus a K-1 for each owner; usually higher accounting fees |
| State taxes and fees | Some states charge S corporations a minimum tax or franchise tax; a few don’t recognize the election or tax it differently |
| Bookkeeping discipline | Clean books, separate accounts, documented distributions and accountable plans for reimbursing expenses |
Worked examples using 2026 rates
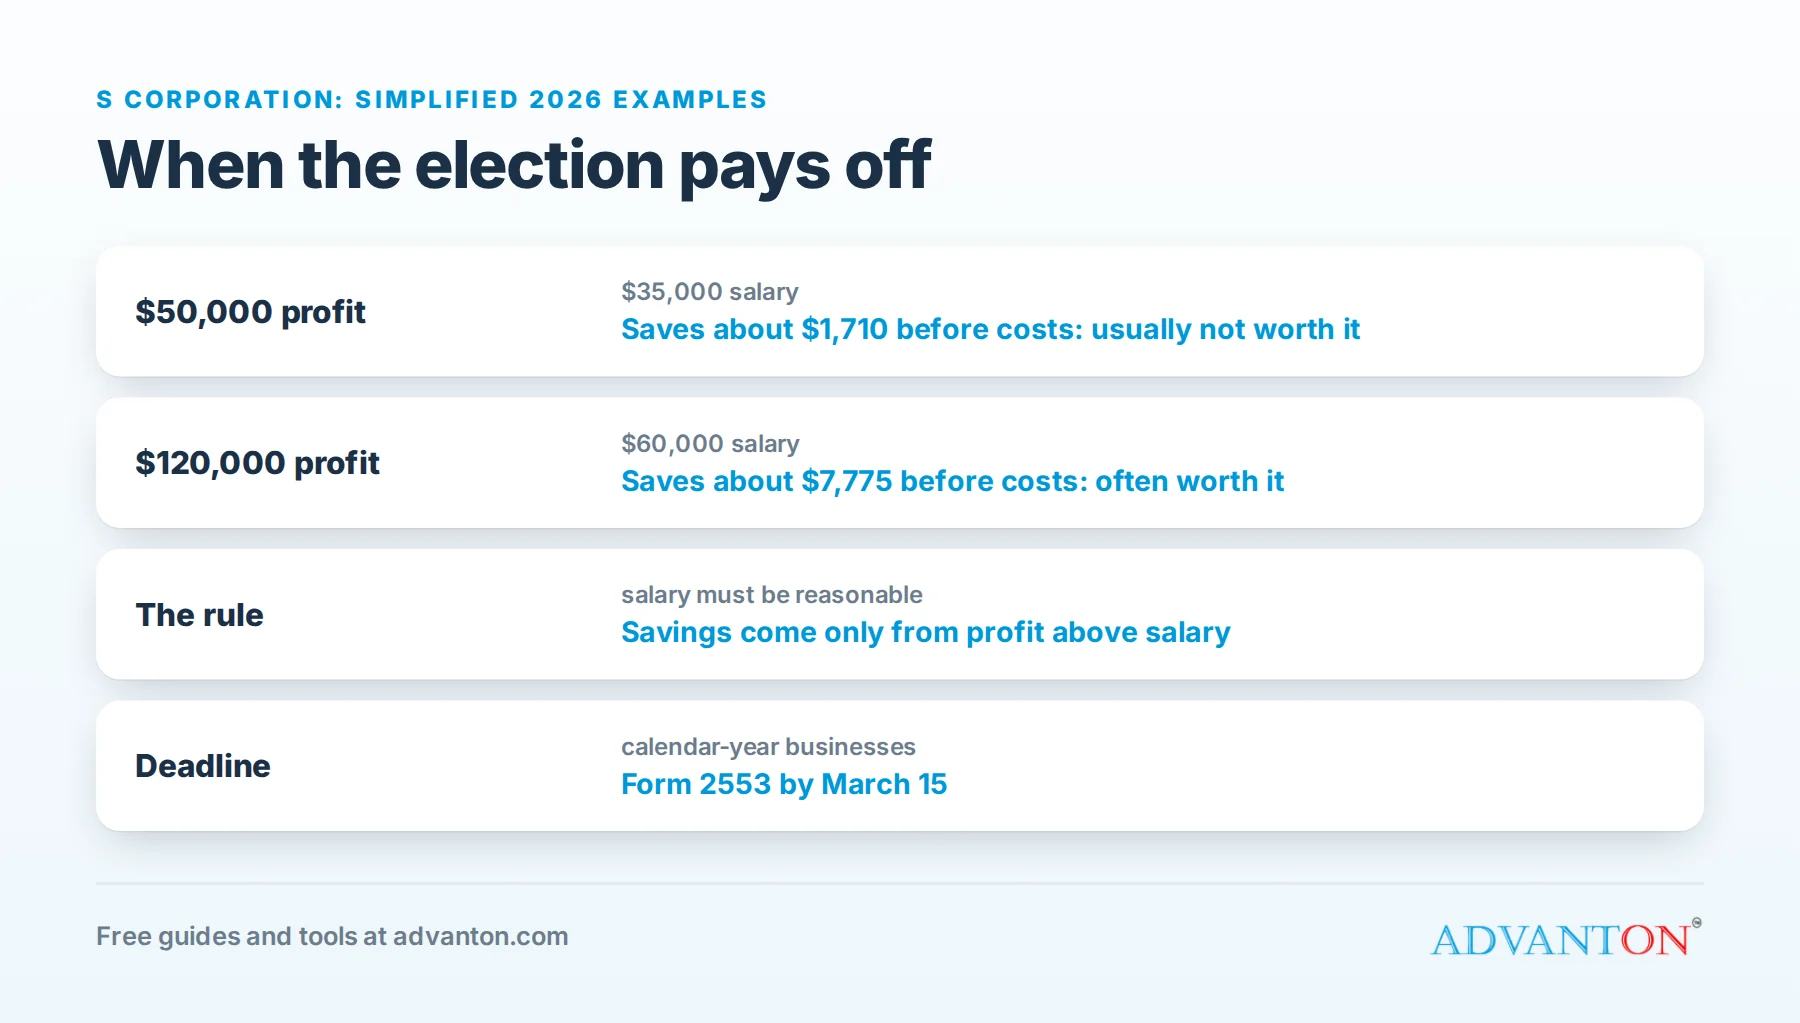
These are simplified illustrations that compare self-employment tax with S corporation payroll taxes only. They ignore income tax brackets, the 20% QBI deduction, state taxes and the employer’s deduction for its share of payroll taxes, so use them to understand the logic, not to make the decision.
Example 1: $50,000 profit
| Without the election | With the election | |
|---|---|---|
| Salary | n/a | $35,000 |
| Self-employment or payroll taxes | About $7,065 | About $5,355 |
| Tax difference | About $1,710 saved |
After paying for payroll services and a business tax return, the savings may disappear entirely. Usually not worth it.
Example 2: $120,000 profit
| Without the election | With the election | |
|---|---|---|
| Salary | n/a | $60,000 |
| Self-employment or payroll taxes | About $16,955 | About $9,180 |
| Tax difference | About $7,775 saved |
Even after extra costs, the owner may save several thousand dollars a year. Often worth considering, if a $60,000 salary is genuinely reasonable for the work.
When an S corporation makes sense
Consider it when:
- Profit is consistent, not a one-off good year.
- Profit is well above a reasonable salary for your role, because the savings come only from the difference.
- You can handle the admin: payroll, clean books and a business tax return, or pay someone to.
- Your state treats it favorably.
It usually doesn’t make sense in your first year (when profit is uncertain), when your reasonable salary would absorb most of the profit, or when you plan to bring in investors who need a different class of stock.
Other effects to know about
- Retirement contributions: contributions to some retirement plans are based on your salary, not total profit, which can reduce how much you can save.
- Health insurance: premiums paid for a more-than-2% shareholder are handled through payroll in a specific way; follow the IRS rules.
- Social Security benefits: a lower salary means lower earnings on your Social Security record, which can affect future benefits.
- QBI deduction: your salary isn’t qualified business income, so a higher salary can reduce your 20% QBI deduction.
S corporation vs C corporation
| S corporation | C corporation | |
|---|---|---|
| Federal income tax on profit | None at the company level; passes through to owners | 21% at the company level |
| Dividends or distributions | Generally not taxed again | Taxed again to shareholders as dividends |
| Owners | Up to 100, US citizens or residents, one class of stock | Unlimited, any type of shareholder, multiple classes of stock |
| 20% QBI deduction | Available to owners | Not available |
| Best for | Profitable small businesses owned by individuals | Startups raising investment, or businesses reinvesting most profits |
How to pay yourself correctly
- Set a reasonable salary and run it through payroll on a regular schedule.
- Take distributions only from profit, after your salary and expenses, and record each one in your books.
- Keep distributions in proportion to ownership. With one class of stock, owners must receive distributions in proportion to their shares; uneven distributions can put the election at risk.
- Reimburse business expenses through an accountable plan, with receipts, instead of paying personal bills from the business account.
- Review your salary each year as the business and your role change.
How some states treat S corporations
- California taxes S corporations at 1.5% of net income, with an $800 minimum.
- New York City doesn’t recognize the S corporation election for its own corporate tax, so S corporations there pay city tax as corporations.
- Texas and Tennessee apply their franchise or business taxes to S corporations and LLCs alike, so the federal election doesn’t avoid them.
- Most other states follow the federal treatment, but check your state’s rules before you elect.
Your yearly S corporation checklist
| When | What to do |
|---|---|
| Every payroll | Pay your salary, withhold taxes and make deposits on time (a payroll service automates this) |
| Quarterly | File Form 941 payroll returns and state payroll filings |
| January | Issue W-2s for owners and employees; file Form 940 for federal unemployment tax |
| By March 15 (calendar year) | File Form 1120-S and give each owner a Schedule K-1 |
| Yearly | File state returns and annual reports, review your reasonable salary, and reconcile distributions |
Red flags: signs an S corporation is set up badly
- No salary, or a token salary, while the owner takes large distributions. This is the single most common reason the IRS questions S corporations.
- Paying personal bills from the business account instead of taking documented distributions.
- Uneven distributions between owners that don’t match their ownership percentages.
- Payroll taxes paid late or not at all. Unpaid payroll taxes carry heavy penalties, and owners can be held personally responsible for them.
- No separate books, so profit, salary and distributions can’t be traced.
- An ineligible owner, such as another company, a partnership or a nonresident alien, which can end the election automatically.
If any of these sound familiar, talk to a CPA soon: many problems can be corrected, especially if they’re caught early.
How to elect, step by step
- Form an LLC or corporation with your state, if you haven’t already.
- Get an EIN. See how to get an EIN.
- Decide your reasonable salary with your CPA, and document how you set it.
- File Form 2553 within the deadline, signed by all shareholders.
- Set up payroll before your first salary payment.
- Keep clean books, and file Form 1120-S each year.
Frequently asked questions
Can a single-member LLC be an S corporation?
Yes. A single-member LLC can elect S corporation tax status by filing Form 2553, as long as it meets the eligibility rules.
Can I revoke an S corporation election?
Yes, with the consent of shareholders holding more than half of the shares. After revoking, you generally can’t re-elect for five years without IRS consent.
What’s a reasonable salary?
What you’d have to pay someone else for the work you do. Look at salary data for similar roles in your area and document your reasoning.
Is an S corporation the same as an LLC?
No. An LLC is a legal structure created under state law; an S corporation is a federal tax status. Many small businesses are LLCs taxed as S corporations.
Do I need a CPA to run an S corporation?
It’s not required, but most owners use one, at least to set a defensible salary and prepare Form 1120-S. Mistakes with payroll and distributions are costly, and the fee is usually small compared with the tax savings.
Can I pay myself bonuses?
Yes. Bonuses paid as wages go through payroll with taxes withheld, and they count toward your reasonable compensation. Distributions are separate and aren’t subject to payroll taxes.
Keep learning
- LLC vs sole proprietorship vs corporation
- Small business taxes and bookkeeping
- Best payroll software for small business
Sources
- IRS, S corporations
- IRS, About Form 2553, Election by a Small Business Corporation
- IRS, S corporation compensation and medical insurance issues
- Journal of Accountancy, Social Security wage base for 2026
Last reviewed October 26, 2026. Startup costs are estimates; check local prices, licensing and tax rules before you commit money.


Leave a Reply