
A mortgage brokerage helps borrowers find home loans by shopping multiple wholesale lenders, then managing the application through closing. Brokers can often find competitive rates and programs that suit borrowers’ situations, while lenders handle underwriting and funding.
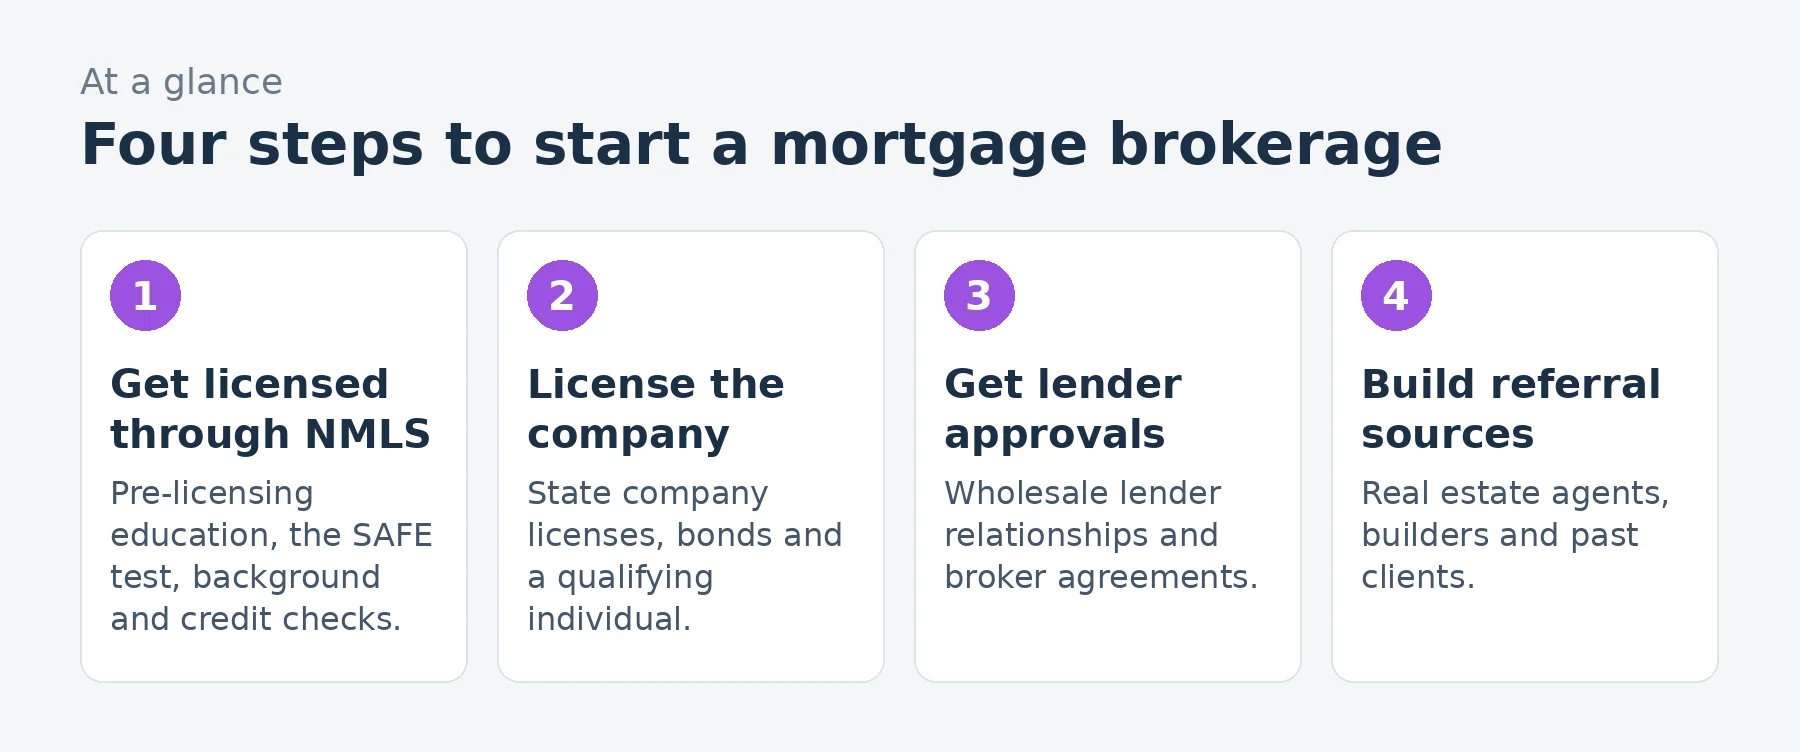
Mortgage origination is heavily regulated. Under the federal SAFE Act, loan originators must be licensed through the NMLS (Nationwide Multistate Licensing System), which requires pre-licensing education, a national test, background and credit checks and continuing education, and brokerages need state company licenses, often with surety bonds. Federal rules also govern how originators are paid, referral fees and required disclosures. Advanton’s mortgage broker data shows a median pay of $76,690 for loan officers (May 2025). This guide covers licensing, lender approvals, rules, technology, marketing, a worked example and a 90-day plan.
A mortgage brokerage at a glance
Table of Contents
| Topic | What to expect |
|---|---|
| Startup cost | Moderate: licensing and education, company licenses and surety bonds, lender approvals, loan origination software, compliance support and marketing |
| Licensing | Individual mortgage loan originator licenses through NMLS, plus a company license in each state where you do business |
| Key rules | Loan originator compensation rules, RESPA limits on referral fees, TRID disclosures and fair lending laws |
| How you earn | Compensation from the lender or borrower on each closed loan, under federal compensation rules |
| Best for | Licensed, relationship-driven originators who manage detail-heavy processes |
Who a mortgage brokerage suits
It suits licensed loan originators who enjoy helping borrowers, managing many moving parts and building referral relationships with real estate professionals. Experience at a lender or brokerage before starting is very valuable.
SAFE Act licensing
- Pre-licensing education: at least 20 hours of NMLS-approved education, including federal law, ethics and nontraditional mortgage lending, plus any state-specific hours.
- The SAFE MLO test: a national exam, with state components handled through the national test.
- Background and credit checks, including fingerprints.
- Continuing education: at least eight hours each year to renew.
- State licenses for each state where you originate loans.
Licensing is managed through the NMLS, which also gives each originator a unique identifier that must appear on certain documents and advertising.
Company licensing and bonds
A brokerage typically needs a company license in each state where it operates, a qualifying individual with experience, a surety bond and sometimes net worth requirements, plus branch licenses for additional offices. Requirements vary by state, so plan the states you will serve from the start.
Wholesale lender approvals
Brokers originate loans through wholesale lenders, which must approve your brokerage before you can submit loans. Approval usually requires licenses, financial information, a broker agreement and sometimes minimum experience. Working with several lenders lets you offer more programs and competitive pricing.
Loan originator compensation rules
Under federal rules, loan originator compensation may not be based on a loan’s terms (such as its interest rate), and an originator may not receive compensation from both the borrower and another party on the same transaction. Originators must also not steer borrowers to loans that pay more unless they are in the borrower’s interest, with safe harbor practices for presenting loan options.
RESPA and referral fees
RESPA Section 8 prohibits kickbacks and referral fees for settlement service business, such as paying real estate agents for referrals. Marketing relationships must be structured carefully, with fair market value for any services actually provided. Get compliance advice before entering marketing agreements.
Disclosures and fair lending
The TILA-RESPA integrated disclosures (TRID) require a Loan Estimate within three business days of an application and a Closing Disclosure at least three business days before closing, with limits on changes. Brokers and lenders coordinate responsibilities. Fair lending laws, including the Equal Credit Opportunity Act and Fair Housing Act, prohibit discrimination, so treat every applicant consistently and document decisions.
Startup costs to plan for
| Item | What to budget for |
|---|---|
| Licensing | Education, test, background checks, license fees |
| Company licenses and bonds | Each state you operate in |
| Technology | Loan origination system, pricing engine, CRM, secure portal |
| Compliance | Policies, quality control, compliance consultant |
| Insurance | E&O and cyber coverage |
| Marketing | Website, referral events, advertising with required disclosures |
Use our startup cost calculator for your total.
How brokers are paid
Brokers are paid on closed loans, either by the lender (lender-paid compensation set in the broker agreement) or by the borrower (borrower-paid), but not both on the same loan. Compensation must follow federal rules and be disclosed. Income depends on loan volume and amounts, so pipeline management matters.
A worked example: a small brokerage
These are illustrative assumptions for a small brokerage with two loan originators, not predictions; compensation depends on loan amounts and lender agreements.
| Assumption | Monthly | |
|---|---|---|
| Broker compensation | 8 closed loans averaging $330,000 at about 1.75% | $46,200 |
| Revenue | $46,200 | |
| Loan originator compensation | Commissions paid to the second originator | $(9,000) |
| Loan processor | With payroll costs | $(5,200) |
| Loan origination software and credit reports | $(1,500) | |
| Licensing, bonds and compliance | Averaged monthly | $(900) |
| Office and technology | $(2,500) | |
| Marketing | $(2,500) | |
| E&O and other insurance | $(400) | |
| Profit before owner pay and taxes | $24,200 |
That leaves about $24,200 a month before the owner’s pay and taxes, on about $46,200 of revenue. Mortgage volume rises and falls with interest rates and the housing market, so keep reserves and diversify referral sources.
Loading the calculator…
A loan process
- Pre-qualify the borrower and review credit, income and assets.
- Compare programs and pricing from wholesale lenders.
- Take the application and issue the Loan Estimate on time.
- Collect documents and submit to the lender for underwriting.
- Clear conditions, order appraisal and coordinate with the title company.
- Close the loan and follow up for referrals.
Finding borrowers
- Real estate agents, through education and service, not referral payments.
- Builders and new construction communities.
- Past clients, for refinances and referrals.
- Financial planners and accountants.
- Local presence: reviews, community events and educational content.
Advertising must include required disclosures, such as your NMLS identifier, and accurate rate information.
Data security
Mortgage files contain Social Security numbers, bank statements and tax returns. Use secure portals, encryption and access controls, and follow the FTC Safeguards Rule’s requirements for financial institutions, including a written information security program.
Rate locks and pricing
Mortgage rates change daily. Explain rate locks, lock periods and what happens if closing is delayed, and document lock agreements. Comparing lender pricing carefully, and presenting options consistently, supports both good advice and compliance with steering rules.
Specialty and non-QM loans
Self-employed borrowers, investors and people with unusual income often need specialty programs, such as bank statement loans or investor cash-flow loans. Knowing these programs helps brokers serve borrowers banks turn away, but explain their higher costs and risks clearly.
Quality control
Lenders and regulators expect accurate applications. Verify information, watch for fraud red flags and run quality control reviews on closed files. Repeated problems can lead lenders to drop your brokerage.
Managing the market cycle
Refinance demand rises when rates fall and collapses when they rise, while purchase volume follows the housing market. Build a business on purchase referrals and repeat clients, keep fixed costs flexible and maintain cash reserves for slow periods.
Common mistakes to avoid
- Originating loans before licenses are approved.
- Paying real estate agents for referrals.
- Compensation that varies with loan terms.
- Late Loan Estimates or Closing Disclosures.
- Weak data security for borrower files.
Your first 90 days
- Days 1-30: complete pre-licensing education and the SAFE test and start your NMLS application.
- Days 31-60: apply for company licenses and bonds, set up technology and compliance policies.
- Days 61-90: secure wholesale lender approvals and build relationships with real estate agents and builders.
Frequently asked questions
What license do I need to be a mortgage broker?
An individual mortgage loan originator license through NMLS, plus a company license in each state where your brokerage operates.
What does SAFE Act licensing require?
At least 20 hours of pre-licensing education, passing the SAFE MLO test, background and credit checks and at least eight hours of annual continuing education.
Can mortgage brokers pay real estate agents for referrals?
No. RESPA Section 8 prohibits referral fees and kickbacks for settlement services.
How are mortgage brokers paid?
By the lender or the borrower on each closed loan, but not both, under federal compensation rules.
What is TRID?
The integrated disclosure rules requiring a Loan Estimate within three business days of application and a Closing Disclosure three business days before closing.
Do I need lender approval?
Yes. Wholesale lenders must approve your brokerage before you can submit loans to them.
How long does it take to get licensed as a loan originator?
It depends on education, testing and state processing; many people complete the process within a few months.
Can a mortgage broker also be a real estate agent?
Sometimes, with both licenses, but dual roles bring disclosure requirements and RESPA considerations; get compliance advice.
How many lenders should a broker work with?
Enough to offer competitive pricing and a range of programs; many brokers start with several wholesale lenders.
Keep learning
- Mortgage brokers industry data
- How to start a credit repair business
- How to start a financial advisor practice
- Startup cost calculator
Sources
- NMLS, SAFE Act licensing requirements for mortgage loan originators
- CFPB, Loan originator rule (compensation and qualifications)
- CFPB, TILA-RESPA integrated disclosures (Loan Estimate and Closing Disclosure)
- CFPB, RESPA Section 8 (kickbacks and referral fees)
- US Bureau of Labor Statistics, Loan officers
Last reviewed November 3, 2026. Startup costs are estimates; check local prices, licensing and tax rules before you commit money.

