
Hail, wind, hurricanes, floods and ice storms damage thousands of homes and businesses every year. When a storm hits, property owners need roofers, restoration companies, tree services, fence and window contractors, electricians and plumbers, often all at once. Storm work can bring a surge of revenue, but it also attracts "storm chasers" who overpromise, pressure homeowners and leave poor work behind.
This guide explains how local contractors can prepare for storms, respond quickly and safely, work honestly with insurance claims, follow the rules that apply, and earn a reputation that lasts long after the storm.
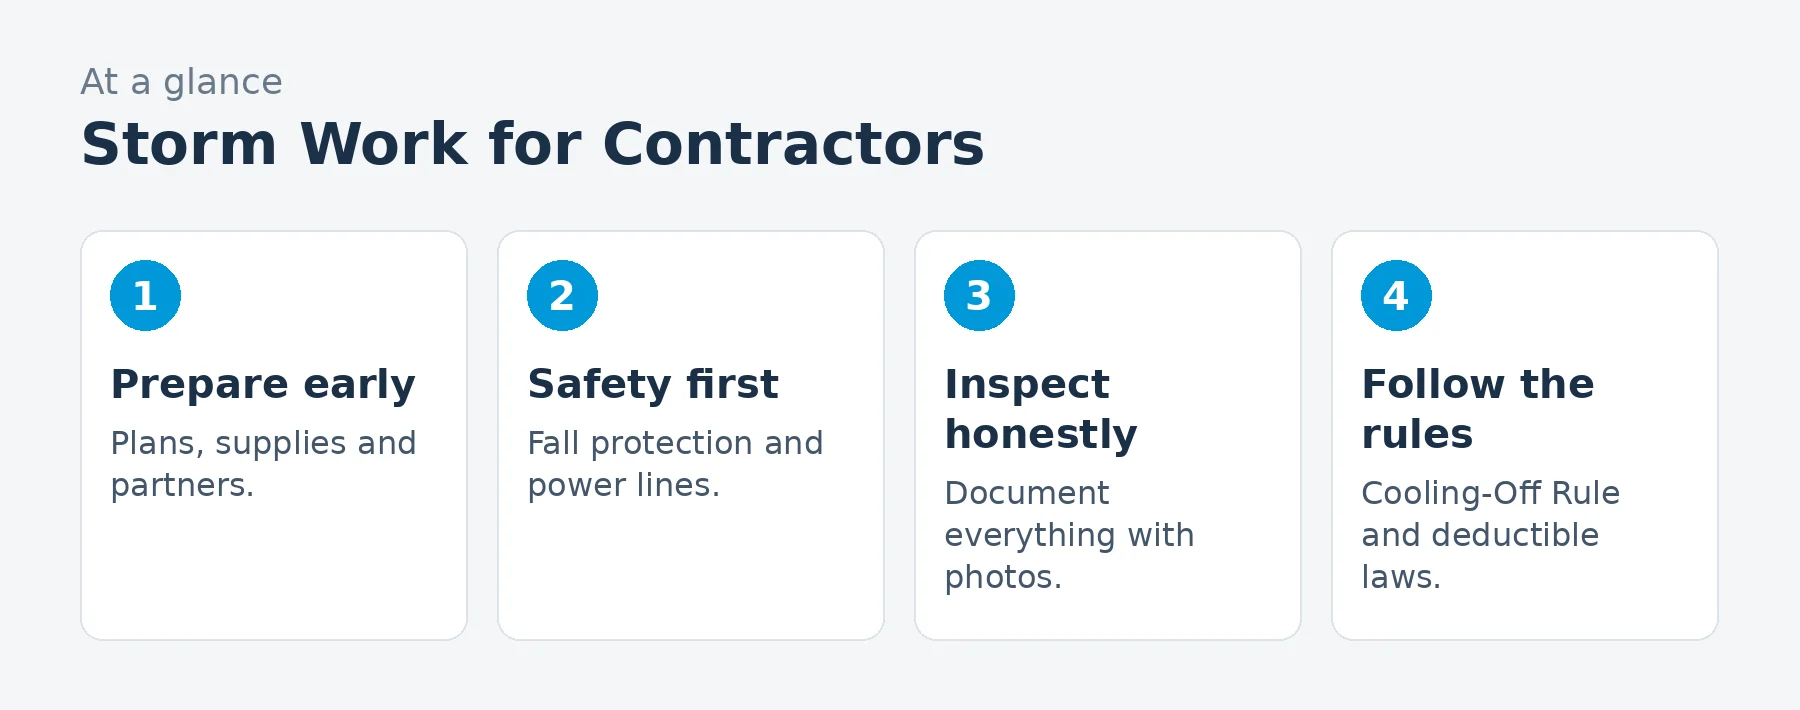
Which trades handle storm work
Table of Contents
| Trade | Typical storm work |
|---|---|
| Roofing | Hail and wind damage, emergency tarping, replacements |
| Restoration | Water extraction, drying, mold prevention |
| Tree service | Fallen trees, hazardous limbs, debris |
| Windows and siding | Broken glass, damaged siding and gutters |
| Fencing | Wind-damaged fences |
| Electrical | Damaged service, generator installs |
| Plumbing | Sump pumps, flooding, frozen pipes |
Prepare before storm season
- Build a response plan: who answers calls, who inspects, how jobs are prioritized.
- Stock emergency supplies: tarps, plywood, fasteners and safety gear.
- Line up partners: suppliers, subcontractors, equipment rental and other trades.
- Prepare paperwork: inspection forms, photo checklists, contracts with required notices.
- Train crews on safety in storm conditions.
- Update your Google Business Profile, website and messaging templates so you can communicate fast.
Respond fast, but safely
After a storm, the first priority is safety: downed power lines, unstable trees and damaged roofs injure workers every year. Inspect from the ground first, use proper fall protection (OSHA requires fall protection for construction work at six feet or more), and never work near energized lines. Prioritize emergency stabilization (tarps, board-ups and water extraction) before full repairs.
Emergency services vs full repairs
Separate the work into two phases. Emergency services (tarping, board-ups, water extraction and tree removal from structures) stop further damage and are usually urgent. Full repairs follow once damage is documented, insurance is involved and materials are available. Price and contract them separately, explain the difference to customers, and don’t pressure anyone into signing for full repairs during an emergency visit.
Inspect honestly
Homeowners are stressed and often unsure whether damage is covered. Give honest assessments with clear photos and explanations, including when damage is minor or not storm-related. Recommending a repair instead of a replacement when that’s the right answer builds trust and referrals. Drone photography can help, but commercial drone use generally requires FAA Part 107 certification.
A documentation checklist
| Document | Why it matters |
|---|---|
| Date-stamped photos of damage and conditions | Supports the claim and your scope |
| Measurements and notes | Accurate estimates |
| Emergency work log | Justifies emergency charges |
| Signed authorizations | Proof the customer approved work |
| Material receipts | Backs up invoices |
| Before-and-after photos | Proof of completed work and quality |
Careful documentation protects you, the homeowner and the claim.
Working with insurance claims
Many storm repairs are paid through insurance. Help homeowners document damage and understand the process, provide clear estimates, and meet adjusters when asked. But know the limits:
- Don’t negotiate claims on a homeowner’s behalf unless you’re licensed as a public adjuster where required.
- Don’t waive or rebate deductibles where state law prohibits it; several states have made this illegal.
- Understand assignment of benefits rules: Florida, for example, prohibits assignment of benefits for residential policies issued on or after January 1, 2023.
- Keep estimates accurate: inflating claims is insurance fraud.
See insurance restoration work for contractors.
Contracts and the FTC Cooling-Off Rule
When you sell to homeowners at their homes, the FTC’s Cooling-Off Rule generally gives buyers three business days to cancel sales of $25 or more, and requires sellers to provide notice of that right. Many states add their own home solicitation and storm-repair contract rules, such as specific cancellation notices. Use written contracts with clear scope, price, schedule, payment terms and required notices.
Price gouging and emergency rules
Many states have price gouging laws that apply during declared emergencies, limiting large price increases for essential goods and services. Some states also require out-of-state contractors to register before working in disaster areas, and local governments may require permits even for emergency repairs. Check state and local rules when a storm is declared.
Don’t become a storm chaser
Homeowners and regulators recognize the warning signs: door-to-door pressure, large upfront payments, out-of-area crews with no local address, offers to "cover your deductible" and pressure to sign before an inspection. The FTC warns consumers about exactly these tactics after disasters. Local contractors win long-term by doing the opposite: clear local presence, honest inspections, reasonable deposits and written contracts.
Pricing, deposits and payment schedules
Price storm work the same way you price normal work, using your real costs, and avoid sudden increases that could violate price gouging laws. Keep deposits reasonable and tied to materials or scheduled work; some states limit how much contractors may collect upfront for residential repairs. Use progress payments for larger jobs, and explain clearly when insurance payments are expected and who pays what.
Communicating during a surge
After a storm, customers want to know when you’ll arrive. Send a quick confirmation for every request, give honest timelines, and update customers when schedules change. Prepared text and email templates save hours: request received, inspection scheduled, estimate sent, materials ordered, work scheduled and work complete. Customers forgive waiting; they don’t forgive silence.
Managing a demand surge
| Challenge | How to handle it |
|---|---|
| Too many calls | Answering service, callback lists and clear timelines |
| Limited crews | Trusted subcontractors, prioritized emergency work, honest scheduling |
| Material shortages | Supplier relationships and early orders |
| Cash flow | Deposits within the law, progress billing and insurance timing plans |
| Existing customers | Prioritize your past and maintenance customers |
Tell customers honestly how long work will take. A realistic date you keep beats a promise you break.
Building trusted relationships ahead of time
Insurance agents, property managers, HOAs and local businesses look for contractors they can recommend after storms. Build these relationships during calm months with clear credentials, insurance certificates and examples of honest work. Agents can’t direct claims improperly, but they appreciate knowing reputable local contractors to suggest when policyholders ask.
Using weather alerts to plan
Follow National Weather Service forecasts and alerts for your area. When severe weather is likely, check crew availability, confirm supplies and prepare your phone and messaging plan before the storm arrives, so you’re ready the moment calls begin.
After the storm: follow up
Storm customers can become long-term clients. Send a thank-you, ask for a review, register warranties and schedule a follow-up inspection. Customers you treat well after a disaster tell their neighbors for years.
Marketing storm services the right way
Storm marketing works best when it’s helpful rather than alarming. Publish storm preparation tips before the season, share what homeowners should do immediately after damage, and explain how insurance claims typically work. After a storm, update your Business Profile with availability and emergency services, and use neighborhood marketing near completed jobs. Avoid scare tactics, exaggerated damage claims and messages that look like official notices; they damage trust and may violate consumer protection laws.
Warranties and quality
Rushed storm work leads to callbacks. Use the same materials, installation standards and inspections you’d use any other time, register manufacturer warranties, and give customers your workmanship warranty in writing.
Common mistakes
- Working unsafely in rushed conditions.
- Overcommitting and missing promised dates.
- Waiving deductibles where it’s illegal.
- Skipping written contracts and required notices.
- Neglecting existing customers for new storm leads.
Frequently asked questions
Is storm work profitable for contractors?
It can be, with preparation, capacity planning and honest pricing, but surges strain crews, materials and cash flow.
Can contractors waive insurance deductibles?
Several states prohibit it; check your state’s laws.
Do homeowners have the right to cancel storm repair contracts?
Under the FTC Cooling-Off Rule, buyers generally have three business days to cancel sales of $25 or more made at their home, and many states add their own rules.
Do out-of-state contractors need to register after disasters?
Some states and localities require registration or licensing; check before working there.
How can local contractors compete with storm chasers?
Local reputation, honest inspections, clear contracts and fast, safe service.
What should I include in a storm repair contract?
Scope, price, schedule, payment terms, insurance responsibilities, warranties and any cancellation notices required by federal and state law.
Should I travel to storm areas outside my market?
It can add work, but check licensing and registration rules, plan lodging and supplies, and consider whether you can support warranties afterward.
How fast should I respond after a storm?
Acknowledge requests the same day, prioritize emergencies and safety, and give honest timelines for full repairs.
How Advanton helps
Advanton is a free resource for small businesses. Create quotes and invoices with the free quote and invoice generator, grow reviews with the review request kit and keep your listing current in the Advanton directory. Advanton earns money when you buy a domain or hosting through our store, which helps keep everything else free.
Keep learning
- Insurance restoration work for contractors
- Roofing marketing calendar
- Water and fire damage restoration industry data
Sources
- Federal Trade Commission, Buyer's Remorse: The FTC's Cooling-Off Rule
- Federal Trade Commission, Hiring a contractor after a disaster
- Occupational Safety and Health Administration, Fall protection in construction
Last reviewed November 1, 2026. Startup costs are estimates; check local prices, licensing and tax rules before you commit money.


Leave a Reply