
Getting a loan for a business that doesn’t exist yet is harder than getting one for an established business, but it’s far from impossible. Lenders mainly want to know two things: will you repay, and what happens if you can’t? New businesses have no track record to answer the first question, so lenders look closely at your plan, your personal credit and finances, your experience, and how much of your own money you’re putting in.
This guide covers where startups can borrow, what each option costs, what lenders require, and how to apply with the best chance of approval.
Startup loan options at a glance
Table of Contents
| Option | Typical amounts | Good for | Watch out for |
|---|---|---|---|
| SBA 7(a) loan | Up to $5 million | Larger startups with a strong plan and some owner money | Paperwork and time; startups usually inject at least 10% |
| SBA Express | Up to $500,000 | Faster SBA-backed loans | Higher maximum rates than standard 7(a) |
| SBA microloan | Up to $50,000 (average about $13,000) | Small startups, owners with limited credit | Small amounts; availability varies by area |
| Bank or credit union loan | Varies | Owners with strong credit and collateral | Banks often prefer businesses with two or more years of history |
| CDFI loan | Usually small to mid-size | Underserved communities, new businesses | Varies by lender |
| Equipment financing | Cost of the equipment | Vehicles, machines, kitchen equipment | The equipment secures the loan |
| Online lender | Varies | Speed, and businesses with some revenue | Often much higher costs |
SBA loans: the backbone of startup lending
The SBA doesn’t usually lend directly. Instead, it guarantees part of loans made by approved lenders, which makes lenders more willing to lend to newer businesses.
SBA 7(a) loans (SBA’s main program):
- Up to $5 million; SBA Express loans up to $500,000.
- SBA guarantees up to 85% of loans of $150,000 or less and 75% of larger loans (50% for Express).
- Terms can reach 25 years for real estate; working capital and equipment loans are typically shorter.
- Maximum interest rates are set by SBA as the prime rate plus a margin that depends on loan size: up to 6.5% above prime for loans of $50,000 or less, 6.0% for $50,001 to $250,000, 4.5% for $250,001 to $350,000, and 3.0% above $350,000. Rates may be fixed or variable.
- Startups are usually expected to contribute at least 10% of the total project cost from their own money (an "equity injection").
SBA microloans go up to $50,000 through nonprofit intermediaries, with interest generally 8% to 13% and terms up to seven years. See SBA microloans explained.
Term loans vs lines of credit
- A term loan gives you a lump sum, repaid in fixed installments over a set period. It suits one-time purchases, such as equipment, a vehicle or a build-out.
- A line of credit lets you borrow up to a limit when you need it, and pay interest only on what you use. It suits uneven cash flow, such as buying materials before a client pays. New businesses often find lines of credit harder to get until they have some history.
Rates and fees: compare like with like
- Fixed rates stay the same for the life of the loan; variable rates move with a benchmark such as the prime rate, so payments can rise.
- Fees can include origination fees, packaging fees and, for SBA loans, a guarantee fee that’s often added to the loan. Ask for every fee in writing.
- APR combines interest and many fees into one yearly rate, making offers easier to compare. Online lenders sometimes quote a "factor rate" instead, which can hide a much higher APR; ask them to convert it.
What lenders look for
- Personal credit. With no business history, your personal credit history matters a lot. Pay down balances and correct errors before applying.
- A business plan with financial projections. Show what you’ll sell, to whom, at what price, your costs, and how the loan will be repaid. The Business Planner builds the numbers lenders ask about.
- Your own investment. Lenders want you to share the risk; 10% or more is common for startups.
- Experience. Industry or management experience reassures lenders that you know the business.
- Collateral. Equipment, property or other assets that secure the loan. SBA lenders take available collateral but may not decline a loan solely for a lack of it.
- Cash flow to repay. Your projections must show payments are affordable, with room for slow months.
- A personal guarantee. Expect to sign one: the Federal Reserve found 59% of small businesses with debt had used a personal guarantee.
How lenders check affordability
Many lenders look at the debt service coverage ratio (DSCR): the cash your business has available to pay debts, divided by the yearly loan payments. A ratio of 1.25 (or higher) is a common benchmark, meaning the business earns $1.25 for every $1 of debt payments.
Worked example: the SBA loan below costs $562 a month, or $6,744 a year. If your projections show $12,000 a year available for debt payments, your ratio is $12,000 ÷ $6,744 = 1.78, comfortably above 1.25. If you could only show $7,000, the ratio would be just 1.04, and many lenders would ask for a smaller loan, a longer term or more owner money.
Collateral: what lenders can use
- Business assets: equipment, vehicles, inventory and receivables.
- Real estate: business property, and sometimes your home for larger loans.
- Cash: savings or certificates of deposit pledged to the lender.
Understand exactly what you’re pledging, and what happens to it if the business can’t repay.
What approval really looks like
According to the Federal Reserve’s 2026 Report on Employer Firms, among small businesses that applied for loans, lines of credit or merchant cash advances, 42% received the full amount, 36% received part, and 22% received nothing. Applicants to small banks had the highest full-approval rate, at 57%. Local banks and credit unions that know your community are often a good place to start.
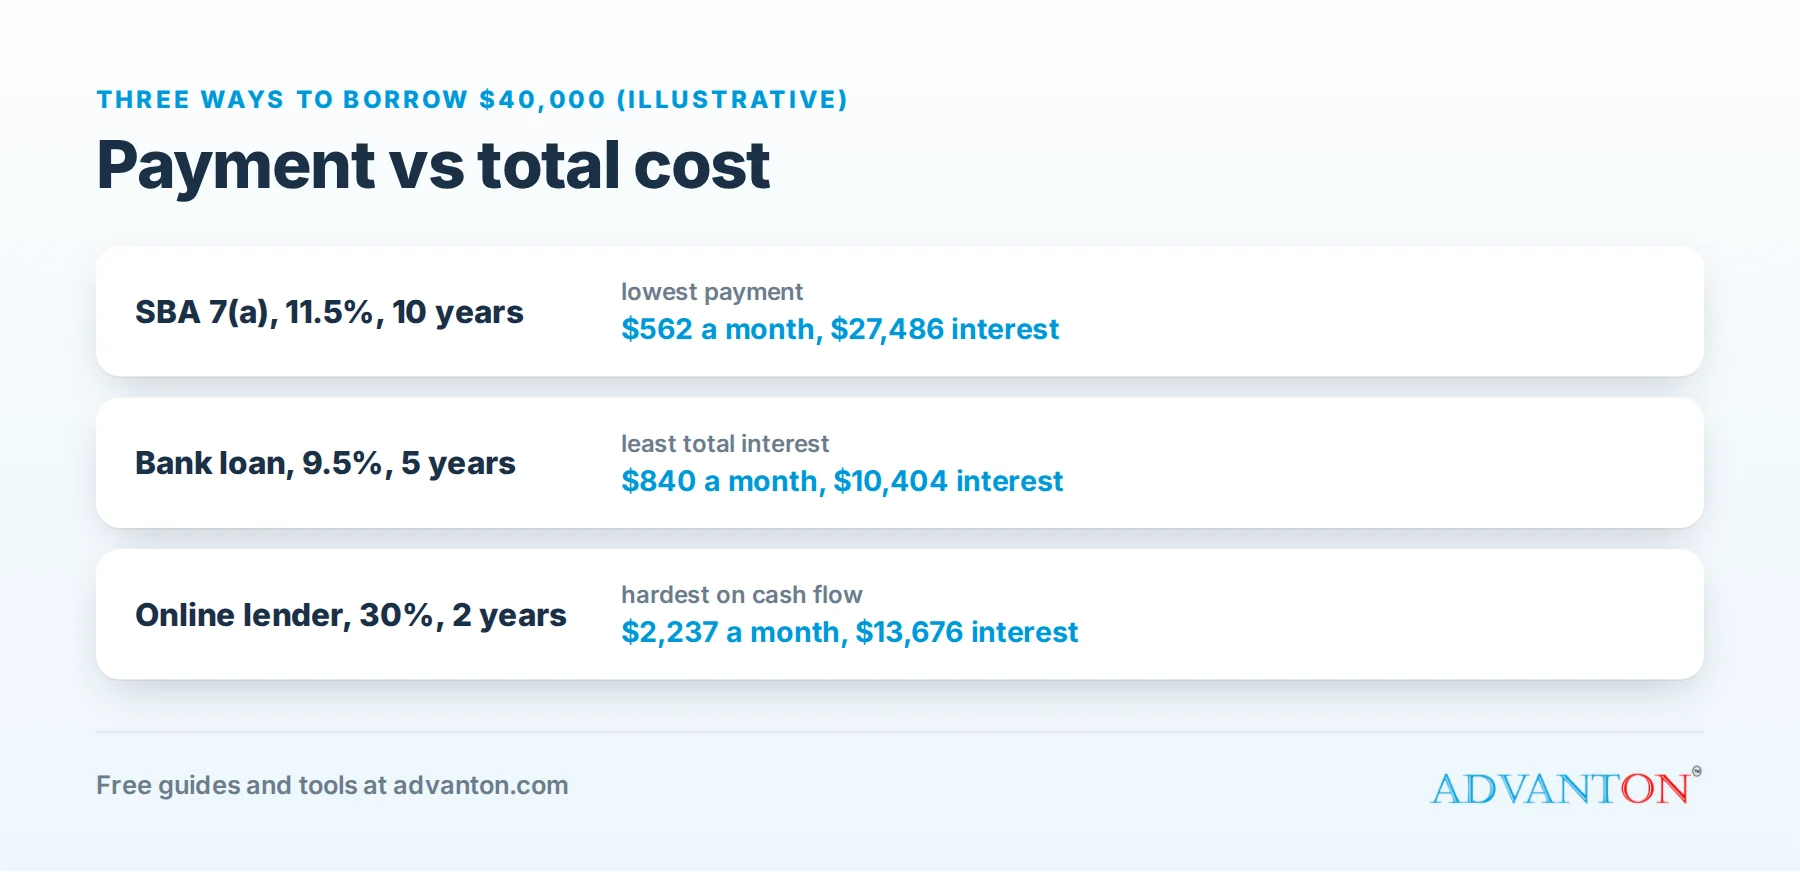
A worked example: three ways to borrow $40,000
These are illustrative rates, chosen to show how terms change the cost. Actual rates depend on the prime rate, your credit and the lender.
| Loan | Monthly payment | Total interest |
|---|---|---|
| SBA 7(a), 11.5% for 10 years | $562 | $27,486 |
| Bank term loan, 9.5% for 5 years | $840 | $10,404 |
| Online lender, 30% for 2 years | $2,237 | $13,676 |
What this shows:
- Longer terms mean lower payments but more total interest. The 10-year SBA loan is easiest on monthly cash flow, but costs the most interest overall.
- High-rate, short-term loans have punishing monthly payments. The online loan’s $2,237 a month could sink a new business in a slow season.
- Compare both the payment and the total cost. Our business loan calculator shows both, plus how much extra payments save.
How to apply, step by step
- Calculate exactly how much you need with a startup cost calculator, including a cash cushion. Borrow for specific purposes, not a round number.
- Check your personal credit and fix errors.
- Write your business plan with three years of projections, and a clear explanation of how the loan will be repaid.
- Gather documents: personal and business tax returns (if any), bank statements, a personal financial statement, licenses, your business formation documents, and resumes for owners.
- Start with local lenders: your bank, local credit unions and community banks. Use SBA Lender Match to find SBA lenders interested in your loan.
- Talk to a free adviser at a Small Business Development Center or SCORE; they can review your plan before you apply.
- Compare offers on total cost, fees, term, collateral and prepayment penalties.
- Read every term before signing, especially the personal guarantee.
Free help before you apply
- Small Business Development Centers (SBDCs) review business plans and loan applications at no cost.
- SCORE mentors are experienced business owners who volunteer to help.
- SBA Lender Match connects you with SBA lenders interested in your type of loan.
- Your local bank’s small business banker can tell you what they need before you apply formally.
A plan reviewed by an adviser is usually stronger, clearer and more likely to be approved, and the advice costs nothing. Book a session a few weeks before you plan to apply.
If you’re turned down
- Ask why. Lenders can explain the main reasons.
- Fix what you can: credit, more owner investment, a clearer plan, smaller loan request.
- Try a microlender or CDFI, which often work with newer businesses.
- Start smaller, prove the concept, and apply again with sales history. Six to twelve months of steady revenue can change a lender’s answer.
Your application checklist
| Item | Notes |
|---|---|
| Business plan with three years of projections | Include how the loan will be repaid |
| Startup cost breakdown | What each borrowed dollar pays for |
| Personal financial statement | What you own and owe |
| Personal tax returns | Often the last two or three years |
| Bank statements | Personal and business |
| Formation documents and licenses | LLC articles, EIN, business licenses |
| Resume | Your relevant experience |
| Collateral details | Descriptions and values |
Personal loans vs business loans
Some owners use a personal loan to fund a new business because it’s easier to get. It can work for small amounts, but it puts the debt in your name, doesn’t build business credit, and often has shorter terms. A business loan, especially an SBA-backed one, usually offers larger amounts and longer terms, and starts building your business’s credit history.
Loans to avoid or approach carefully
- Merchant cash advances, whose effective costs can be extremely high.
- Loans with large upfront fees or pressure to sign immediately.
- Anyone guaranteeing approval regardless of credit. That’s a common scam.
Common mistakes
- Borrowing too little, with no cushion, and needing to borrow again on worse terms.
- Borrowing too much, with payments the business can’t support.
- Choosing a loan by monthly payment alone.
- Using business loans for personal expenses.
- Applying to many lenders at once without preparation, which can hurt your credit and waste time.
Frequently asked questions
Can I get a startup loan with no revenue?
Yes, though it’s harder. SBA loans, microloans and CDFIs lend to startups with a strong plan, owner investment and good personal credit.
What credit score do I need?
There’s no single number; requirements vary by lender and program. Better credit means more options and lower rates. Microlenders and CDFIs are often more flexible.
How long does an SBA loan take?
Standard SBA loans can take several weeks or more; SBA Express is designed to be faster. Microloans vary by intermediary.
Do I need collateral for an SBA loan?
SBA lenders generally take available collateral, especially for larger loans, but a lack of collateral alone isn’t supposed to be the only reason an SBA loan is declined. Smaller loans often have lighter collateral requirements. Ask each lender about its policy.
Keep learning
Sources
- U.S. Small Business Administration, 7(a) loan program terms, conditions and eligibility
- U.S. Small Business Administration, Microloans
- Nav, SBA 7(a) loans: rates, terms and requirements (startup equity injection)
- Federal Reserve Banks, 2026 Report on Employer Firms (Small Business Credit Survey)
Last reviewed October 28, 2026. Startup costs are estimates; check local prices, licensing and tax rules before you commit money.


Leave a Reply