
If you need a modest amount of money to start or grow a small business, and a bank loan feels out of reach, an SBA microloan is often the best place to look. Microloans are small loans, up to $50,000, made by nonprofit, community-based lenders that also offer training and support. They’re designed for exactly the businesses banks often turn away: startups, very small businesses and owners still building credit.
This guide explains how microloans work, what they cost, who qualifies, how to apply, and how they compare with other options.
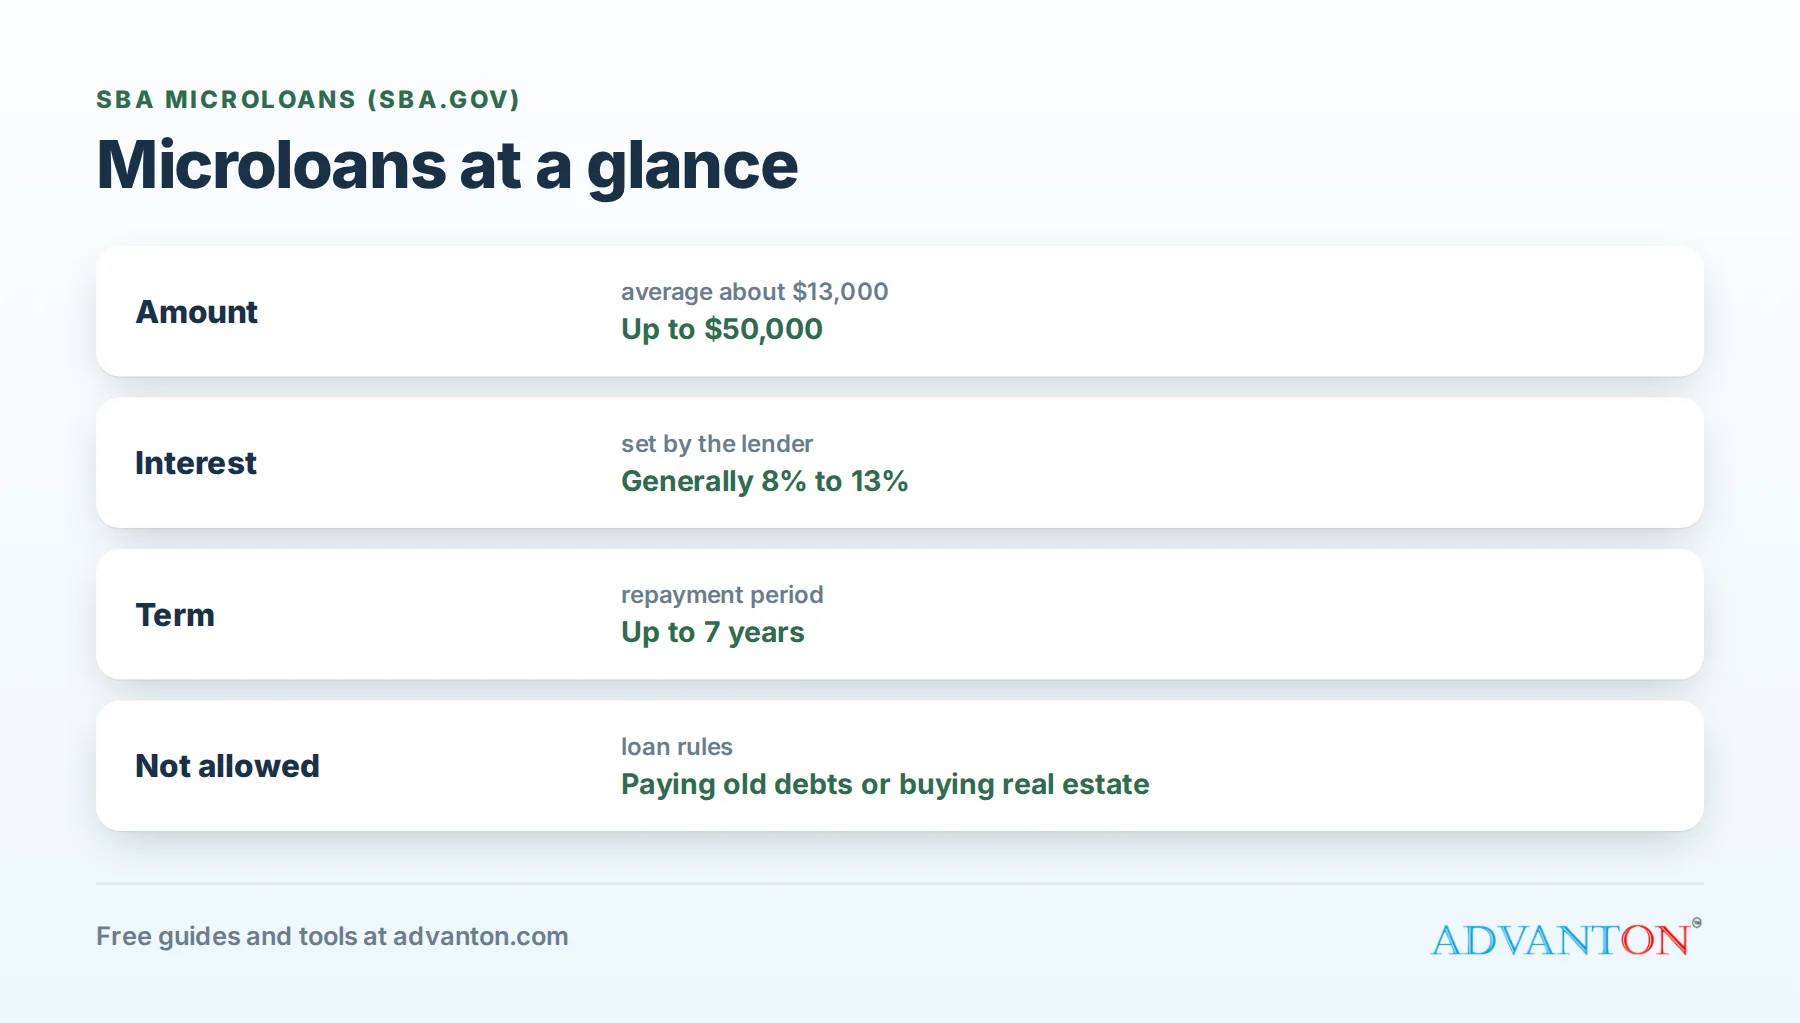
SBA microloans at a glance
Table of Contents
| Feature | Details |
|---|---|
| Loan amount | Up to $50,000; the average is about $13,000 |
| Interest rate | Varies by lender, generally 8% to 13% |
| Maximum term | Seven years |
| Who lends | SBA-approved nonprofit intermediary lenders |
| Who decides | The intermediary makes all credit decisions and sets terms |
| Uses | Starting and growing a business: working capital, inventory, supplies, furniture, fixtures, machinery and equipment |
| Not allowed | Paying existing debts or buying real estate |
| Extras | Many intermediaries provide business training and technical help |
How the microloan program works
The SBA doesn’t lend microloans directly. Instead, it provides funds to intermediary lenders: nonprofit, community-based organizations with experience in lending and in helping small businesses. These intermediaries make the loans to business owners, set their own credit requirements within SBA’s rules, and decide who’s approved.
Because each intermediary sets its own requirements, two microlenders can have quite different rules, interest rates and collateral expectations. It’s worth contacting more than one if you have options in your area.
Who qualifies?
According to the SBA, to be eligible, a business must generally:
- Be an operating business, or about to start one.
- Operate for profit. (Certain nonprofit childcare centers are an exception.)
- Be located in the United States.
- Be small under SBA size standards.
- Not be an ineligible type of business under SBA rules.
Beyond that, each intermediary looks at your business plan, your personal credit history, your experience, your ability to repay and any collateral. Many microlenders are more flexible than banks, and some focus on specific communities, such as women, veterans, minority-owned businesses, rural areas or low-income neighborhoods.
What you can use a microloan for
- Working capital: covering costs while sales build.
- Inventory and supplies.
- Furniture and fixtures.
- Machinery and equipment.
- Getting started: many of the one-time costs of opening.
You can’t use a microloan to pay off existing debts or to buy real estate.
What does a microloan cost? Worked examples
These are illustrative payments, using rates within the typical 8% to 13% range:
| Loan | Rate and term | Monthly payment | Total interest |
|---|---|---|---|
| $13,000 (the average) | 10%, 5 years | $276 | $3,573 |
| $13,000 | 8%, 6 years | $228 | $3,411 |
| $13,000 | 13%, 6 years | $261 | $5,789 |
What this shows: the rate makes a real difference over the life of the loan; the 13% loan costs about $2,400 more in interest than the 8% loan over the same term. Compare offers from different intermediaries where you can, and ask about fees as well as interest. Try your own numbers in our business loan calculator.
A sample "use of funds"
Lenders want to see exactly where the money goes. Here’s an illustrative plan for a $13,000 microloan for a mobile dog grooming business:
| Use | Amount |
|---|---|
| Grooming table, dryer, clippers and tools | $4,200 |
| Van fit-out: water tank, plumbing and power | $5,300 |
| Starting supplies: shampoos, towels, cleaning | $900 |
| Insurance (first months) and licenses | $1,100 |
| Launch marketing: signs, cards, local ads | $1,500 |
| Total | $13,000 |
Every line ties to revenue: the equipment and van fit-out let the business serve customers, and the marketing brings the first ones in.
What microlender training looks like
Many intermediaries pair loans with business support, such as workshops on bookkeeping, marketing and cash flow, one-to-one coaching, and help writing or improving your business plan. Some require a short course before lending; others offer it alongside. Owners often say the support was as valuable as the money.
How to apply, step by step
- Work out how much you need, and exactly what it’s for, with a startup cost calculator. Ask for what you need, not the maximum.
- Find microlenders near you. The SBA’s website lists authorized intermediary lenders by state; your local Small Business Development Center can also point you to them.
- Contact two or three intermediaries. Ask about their requirements, interest rates, fees, collateral, timelines and any training they require or offer.
- Prepare your documents: a business plan (a short one is often fine for small loans), personal financial information, tax returns if you have them, business licenses and registration, and a description of how you’ll use the money.
- Complete any required training. Some intermediaries require business training before or alongside the loan, and it’s often genuinely useful.
- Apply, answer follow-up questions, and review the loan agreement carefully before signing.
- Repay on time. A repaid microloan builds the credit history that makes larger loans easier to get.
Programs for specific communities
Many microlenders focus on particular groups or places, and some offer extra support:
- Women entrepreneurs, often in partnership with Women’s Business Centers.
- Veterans and military spouses.
- Minority-owned businesses and immigrant entrepreneurs.
- Rural businesses and specific counties or neighborhoods.
- Low- and moderate-income owners.
Ask local intermediaries and your Small Business Development Center which programs match your situation.
After you’re approved
- Use the money exactly as planned, and keep receipts.
- Set up automatic payments so you never miss one.
- Track results: did the equipment or marketing produce the sales you expected?
- Keep your lender informed, especially if a slow month threatens a payment; lenders can often help if you call early.
- Stay in the training and coaching, which can help you through problems before they become serious.
How a microloan builds your credit
A repaid microloan is a strong track record. It shows future lenders that you borrowed responsibly, used the money well and repaid on time, which can open the door to larger SBA or bank loans as your business grows.
Microloans vs other options
| Option | Amount | Best for | Trade-off |
|---|---|---|---|
| SBA microloan | Up to $50,000 | Startups and small businesses, flexible lenders, built-in support | Small amounts; availability varies by area |
| SBA 7(a) loan | Up to $5 million | Larger needs with a strong plan | More paperwork; startups usually contribute at least 10% |
| CDFI loan | Varies | Underserved communities and new businesses | Terms vary by lender |
| Credit card | Credit limit | Small, short-term costs | Often high interest |
| Online lender | Varies | Speed, for businesses with revenue | Often much higher costs |
Questions to ask a microlender
- What interest rate and fees would apply to a loan like mine?
- What credit history, collateral and personal guarantee do you require?
- Do you require training, and what support do you offer after the loan?
- How long does approval usually take?
- Can I repay early without a penalty?
- Do you report payments to credit bureaus, so repaying builds my credit?
Is a microloan right for you?
A microloan is usually a good fit if:
- You need less than $50,000, for clear business purposes.
- You’ve been turned down by banks, or don’t yet have the history banks want.
- You’d value coaching alongside the money.
It may not be the best fit if you need a large amount, want to buy real estate, or need to refinance existing debt.
A typical path: from microloan to larger loans
- Year one: borrow a modest microloan to buy equipment and start trading, and repay on time.
- Year two: with a year of sales and a clean repayment record, qualify for a larger microloan or a small bank line of credit.
- Year three and beyond: with steady revenue, apply for an SBA 7(a) or bank loan to expand.
Each step builds the track record that makes the next one easier and cheaper.
Tips to improve your chances
- Show you’ve done the math: realistic costs, prices and sales, with a clear repayment plan. The Business Planner builds these numbers step by step.
- Put in some of your own money, even a little; it shows commitment.
- Explain any credit problems honestly, and what you’ve done since.
- Highlight your experience in the industry or in running a business.
- Take the training seriously. Lenders notice owners who engage.
- Ask for feedback if you’re turned down, and reapply after addressing it.
Documents to have ready
| Document | Why lenders ask |
|---|---|
| Business plan or summary | Shows what you’ll do and how you’ll repay |
| Use of funds | Shows exactly where the money goes |
| Personal financial statement | What you own and owe |
| Tax returns, if any | Your income history |
| Bank statements | Your cash and spending patterns |
| Business registration and licenses | Proof the business is legitimate |
| Quotes for equipment or supplies | Backs up your costs |
Watch out for look-alike scams
Real SBA microloans come through SBA-approved nonprofit intermediaries, and the SBA itself doesn’t charge you to apply. Be wary of anyone who calls or messages offering "guaranteed SBA approval", asks for upfront fees to process a loan, or pressures you to decide immediately. Find intermediaries through the SBA’s website or your local Small Business Development Center.
Common mistakes
- Borrowing the maximum when a smaller loan would do.
- Not comparing intermediaries when more than one serves your area.
- Planning to use the money to pay off old debts, which isn’t allowed.
- Skipping the business plan because the loan is small.
- Missing payments, which damages the credit history you need for the future.
Frequently asked questions
Can startups get SBA microloans?
Yes. Microloans are designed to help businesses start up and expand, and many borrowers are new businesses.
Do I need good credit?
Requirements vary by intermediary. Many microlenders work with owners who have limited or imperfect credit, especially if the plan is strong.
Do I need collateral?
Often, yes, along with a personal guarantee, but requirements vary by lender.
How long does it take?
It varies by intermediary and by whether training is required. Ask each lender for its typical timeline.
Can I get more than one microloan?
The amount you can owe under the program is generally limited to $50,000 in total, and each lender has its own rules, so ask your intermediary. Repaying one loan on time can help you qualify for more later.
Can I pay myself from a microloan?
Microloans are for business purposes, such as working capital, equipment and supplies. Whether a reasonable owner’s draw counts as working capital depends on the lender, so ask before you plan on it.
Is a microloan better than a credit card?
For larger or longer-term needs, usually yes: microloan rates are typically lower than many credit card rates, the payments are fixed, and repaying builds a business lending record. A card can still be handy for small, short-term purchases you’ll repay within weeks, before interest builds up.
Keep learning
Sources
- U.S. Small Business Administration, Microloans
- U.S. Small Business Administration, 7(a) loan program terms, conditions and eligibility
Last reviewed October 28, 2026. Startup costs are estimates; check local prices, licensing and tax rules before you commit money.


Leave a Reply